My Comments on the BNC Report: Price Is Not Necessarily Market Value

The recent Bilyonaryo News Channel (BNC) report featuring Cuervo Appraisers President Jose Maria Fernandez-Cuervo raises important concerns about the reliability of property transaction records in the Philippines, particularly the alleged understatement of selling prices in deeds of absolute sale and the absence of a comprehensive Multiple Listing Service (MLS).

These concerns are relevant to professional valuation practice. However, I believe the discussion should extend beyond the availability and accuracy of recorded selling prices to the broader economic foundations of property valuation.

First, price and market value are not necessarily the same.

Price refers to the amount asked, offered, or actually paid for a property. Market value, on the other hand, is an estimate of the amount for which a property should exchange under defined market conditions, involving knowledgeable and willing parties acting without compulsion.

Even if every deed of absolute sale accurately reflected the consideration paid, the recorded prices would not automatically represent market value. Appraisers must still examine the circumstances surrounding each transaction, including whether it was conducted at arm’s length and under normal market conditions.

Second, the absence of an MLS should not be confused with the absence of reliable valuation methodology.

An MLS primarily facilitates the sharing of property information among real estate professionals. Some systems also record completed transactions, but an MLS does not necessarily provide independently verified selling prices.

While a comprehensive MLS or verified sales database would improve market transparency, neither is an absolute prerequisite for developing a credible opinion of market value.

Third, sales transactions constitute only one source of market evidence, and the Sales Comparison Approach is only one of the recognized valuation approaches.

Professional valuation also recognizes the Income Approach and Cost Approach. The applicability of these approaches depends on the nature of the property, the valuation objective, and the quality of available evidence.

More importantly, property valuation requires an understanding of the economic factors influencing value, including supply and demand, accessibility, location, land-use regulations, highest and best use, income-generating potential, development costs, and prevailing market conditions.

These factors help explain why properties command different prices and how market participants assess their economic benefits.

Fourth, incomplete or unreliable transaction information requires broader market investigation, not simply numerical adjustments.

Adjustments to comparable sales are legitimate valuation tools when supported by market evidence. However, adjustments alone cannot establish market value, particularly when the underlying transaction information is unreliable.

Appraisers must investigate the available evidence, evaluate its relevance, examine the economic characteristics of the property, and reconcile the findings using appropriate valuation approaches.

This is where the distinction between collecting prices and undertaking professional valuation becomes particularly important.

Finally, the reported understatement of consideration in deeds of sale is a legitimate concern that deserves further empirical investigation. Even assuming that such practices are widespread, the implications for valuation should be understood within the broader framework of property market economics.

The central challenge is not merely the absence of an MLS or the reliability of recorded selling prices. It is how professional appraisers interpret available market information and translate it into a credible and defensible opinion of market value.

Property valuation is not simply the process of collecting selling prices and adjusting comparable properties. It is an economic analysis of the property, its market, and the factors influencing its exchange value.

Ultimately, price is evidence, market value is the conclusion, and valuation is the economic analysis connecting the two.

Augusto B. Agosto
Economist | Licensed Real Estate Consultant | Real Estate Appraiser

Will Metro Manila’s Real Estate Market Fall?

Condominium oversupply, geopolitical risk, and the 2028 election: an economic view

Metro Manila’s condominium market is under strain. Thousands of units remain unsold, vacancies are high, and rents in several districts are still far below their pre-pandemic levels. Some observers see structural oversupply; others argue that good location and management still set strong properties apart from weak ones.

The real question is broader: is this an ordinary real estate cycle, or a structural imbalance that global instability and the 2028 presidential election could prolong?

The evidence points to the second, but not to a crash. Metro Manila is going through a slow, uneven adjustment caused by a mismatch between the housing being built and what households can actually afford.

What the numbers show

Unsold condominium inventory stood at about 82,900 units in the second quarter of 2026, enough for 34 months of sales. By the third quarter it had dropped to about 80,000 units and 28 months, as take-up rose 17% to 8,454 units. Demand has not disappeared. But one good quarter does not clear an inventory that would still take more than two years to sell, and residential vacancy remains near 25%.

The adjustment is also uneven. Second-quarter rents compared with pre-pandemic levels:

DistrictRent (₱/sq.m./month)Change vs. pre-pandemic
Bay Area / Pasay706−59%
Alabang / Muntinlupa715−42%
Ortigas / Mandaluyong729−25%
Makati887−18%
Bonifacio Global City1,105+0.1%
Other Taguig715+15%

The Bay Area was hit hardest: heavy new supply, followed by the loss of tenants after the 2024 ban on offshore gaming operators (POGOs), left vacancy there near 58%. BGC, by contrast, has held its ground. There is no single Metro Manila condominium market, only district markets in very different conditions.

A housing shortage alongside unsold units

Metro Manila had a housing backlog of about 819,000 units in 2025, yet some 80,000 condominium units sit unsold. The contradiction disappears once we separate housing need from effective demand: what households are actually able to pay for at today’s prices. Developers build for the second, not the first.

The numbers make the gap plain. The median NCR family earned about ₱33,672 a month in 2023 (PSA Family Income and Expenditure Survey). Two-thirds of unsold units are priced between ₱4 million and ₱12 million. A ₱4 million unit with 20% down, a 20-year loan, and an illustrative 7% interest rate costs about ₱24,800 a month: roughly 74% of that family’s income, before dues, utilities, and taxes. A ₱12 million unit would cost more than twice the family’s entire monthly income.

Metro Manila does not have too much housing. It has too much of the wrong housing for the households that need it.

Why prices have not crashed

Real estate adjusts slowly. Developers and owners carry loans and sunk costs, and many expect a recovery, so they resist cutting list prices. The correction shows up first in other ways: longer selling periods, promotional discounts, rental concessions, and postponed launches. Watching list prices alone understates how far the adjustment has already gone.

Investor demand adds another layer. Many units were bought for rental income and capital gains, not to live in. When rents fall, returns shrink, investors stop buying, absorption slows, and rents come under further pressure. That cycle is hardest on investors who rely on rent to pay their own loans.

Good management helps individual buildings, but it mostly draws tenants from competing buildings. One property’s success is not the market’s recovery.

Global shocks and the 2028 election

The Philippines imports most of its fuel and depends heavily on remittances, so trouble abroad reaches the housing market quickly. Higher oil prices feed inflation and squeeze household budgets. Persistent inflation keeps interest rates and mortgage costs high. Conflict in host countries can hit overseas Filipino workers and the remittances that fund many home purchases. None of this adds supply; it simply weakens the demand needed to absorb the existing stock.

The May 2028 election adds domestic uncertainty. Real estate involves large, long-term commitments that are hard to reverse, so developers and investors often wait for policy direction to become clear. That waiting cuts both ways. Fewer launches would help clear the oversupply, but prolonged hesitation could slow investment and job growth. What matters is not who wins but whether economic policy stays predictable and credible.

So, will prices fall?

Three paths are possible to 2028:

  • Stabilization: energy prices and inflation ease, borrowing gets cheaper, incomes rise, and the inventory is gradually absorbed.
  • Prolonged adjustment: affordability stays tight and investors return slowly. Vacancies persist in oversupplied districts and effective prices drift lower in places.
  • Adverse shock: a new geopolitical crisis brings higher inflation and tighter credit. Combined with forced selling by stretched investors, it produces a deeper, longer correction.

The second path is the most likely. A full collapse cannot be inferred from condominium oversupply alone. That would take widespread financial distress, heavy leverage, and forced selling across other property sectors, and the evidence for those is not there.

A correction would not be all bad. Lower rents leave tenants more to spend, more affordable units improve access to jobs, and less speculative building frees capital for productive uses. Rising prices are not proof of economic success, and falling prices are not proof of failure.

The real question is not whether Metro Manila’s property prices will fall. It is whether the coming adjustment will finally close the gap between the housing being built and the housing Filipinos can actually afford.

*Figures are from published Q2–Q3 2026 property-market research and the PSA 2023 Family Income and Expenditure Survey; the scenarios are conditional assessments, not price forecasts.

Augusto B. Agosto is an economist and a licensed real estate consultant, appraiser, and environmental planner.

Where Engineering Ends and Appraisal Begins: Lessons from the Cost Approach

In the previous article, I discussed the relationship between engineering and appraisal, particularly when valuation involves buildings, machinery and equipment, and other technically complex improvements.

Real estate appraisal is the professional domain of the appraiser. The increasing technical complexity of a property does not change that. What it does change is the nature and extent of the technical evidence the appraiser may need from engineers and other specialists in developing a credible opinion of value. Engineers provide essential evidence about the physical asset — its specifications, capacity, condition, performance, technical life, and replacement requirements.

Subscribe to continue reading

Subscribe to get access to the rest of this post and other subscriber-only content.

When One Property Has Three Possible Futures

Insights from Practice

Reflections from a Development Advisory Engagement

Every property has a story.

Some stories are about families preserving generations of ownership. Others involve investors searching for opportunities or businesses planning their next expansion. Occasionally, a property presents something more challenging — not because of what it is today, but because of what it could become.

One such engagement brought me to Batangas.

Every consulting engagement begins long before the first client meeting. Thus, whenever I receive an inquiry, I make it a point to review any available information before meeting with the client. Property titles, tax declarations, zoning certifications, planning documents, location maps, aerial imagery, and publicly available information often provide valuable context about the assignment. This preliminary review allows me to understand not only the property itself, but also the questions that are likely to shape the engagement.

Continue reading “When One Property Has Three Possible Futures”

How Econometric Analysis Solved a Client’s Valuation Challenge in BGC

In today’s volatile property market, even fully leased buildings can face uncertainty when interest rates rise and yields compress. One of our clients is a developer with a 30-storey, 76-unit office tower in Bonifacio Global City. They sought clarity on whether their investment was still performing as expected. Through econometric analysis, we transformed complex market data into actions. This gave them financial insight that helped them see beyond occupancy rates. They focus on true value, risk, and return.

The Client’s Challenge

A private developer approached our team with a critical question:

“Is our 30-storey, 76-unit office building in Bonifacio Global City still financially viable under current market conditions?”

The client had completed construction two years earlier. The building was fully leased. They were concerned about rising interest rates. Modest rental escalations are eroding investment returns.

The property’s leasing structure appeared competitive. It includes a mix of bare-shell and fitted office units. These units range from PhP1,500 to PhP1,800 per sqm per month. However, management wanted to know if the building’s cash flows truly reflected its economic value. They questioned whether adjustments in pricing, escalation, or capital structure were necessary.

In short, the challenge was not occupancy — it was understanding profitability in a tightening capital market.

Our Approach

Instead of relying on conventional yield assumptions, our team applied econometric modeling. This is an analytical framework that links property-level performance to measurable macroeconomic drivers.

We began by reconstructing the building’s income statement. We also reconstructed rental schedules across 76 office units and all 30 floors. We factored in current lease terms and 3% annual escalations. Additionally, we used observed market data from Pinnacle Real Estate Consulting and Arcadis Philippines.

From there, we derived two distinct discount rates using both finance-based and property-specific risk models:

MethodFormulaResult
Finance-Based (CAPM)R=Rf+β(ERP)+SRP17.40%
Real Estate Build-UpR=Rf+∑RiskPremiums13.16%

Each parameter was anchored to empirical data. This includes the risk-free rate, beta, and risk premiums. These were tied to data from the Bangko Sentral ng Pilipinas, PSA inflation series, and Damodaran’s country risk tables.

By integrating these variables, we aligned the building’s valuation with economic reality rather than static, one-size-fits-all assumptions.

Findings: Translating Data into Decision

Our projection model covered a 10-year period, reflecting the economic life of the building’s interior improvements.

Discount RatePresent Value of Cash Flows (PhP)Fit-out & Equipment Cost (PhP)NPV (PhP)Interpretation
13.16%11,801,35812,472,358–671,000Breakeven (stabilized scenario)
17.40%10,655,64612,472,358–1,816,000Slightly negative (equity scenario)

Despite the modest NPV results, the cash inflows were sufficient to recover the capital outlay within the project’s economic life. This indicated a financially balanced asset — not speculative, but self-sustaining and capital-preserving.

The key insight for the client was that profitability was not being lost. It was simply redefined by changing macroeconomic conditions. In other words, the property’s yield had adjusted to reflect a maturing market.

We extended the analysis to examine how the project would perform under various economic shocks:

  • A 1% increase in the discount rate (e.g., due to rising interest rates) would reduce the property’s value by approximately PhP700,000.
  • A 1% increase in rental escalation would improve valuation by about PhP500,000.

This confirmed that interest-rate and capital-market movements have a greater effect on value than marginal rental adjustments.

The adopted PhP1,800 per sqm rate for fitted offices is advantageous. It places the property squarely within the prime BGC rental range of PhP1,400–PhP1,900. The effective yield is 7–8% per annum. This is a level consistent with institutional benchmarks in Metro Manila’s investment-grade office sector.

The results of the econometric analysis allowed the client to make well-informed and financially sound decisions. Our findings confirmed the current rental rate structure of PHP 1,500 to PHP 1,800 per square meter per month. This rate was aligned with prevailing market conditions. These rates match the conditions in Bonifacio Global City. Attempting to increase the rates further would risk higher tenant turnover without producing a proportional increase in building value. Hence, the most strategic course was to maintain existing rents, ensuring consistent occupancy and stable revenue streams.

Second, the study validated the client’s 3% annual escalation policy. It demonstrated that this policy accurately reflected the average inflation rate. It also matched the standard lease renewal adjustments in the area. This approach ensured that income growth would remain sustainable and competitive, balancing tenant affordability with long-term asset performance.

Finally, we advised the client to reclassify the building’s investment profile—from a short-term growth-driven asset to a core income property. This repositioning recognized that the building had already reached stabilization, with 100% occupancy and predictable cash inflows. The property could now serve as a capital preservation anchor within the client’s portfolio. It would provide reliable income to offset higher-risk, higher-yield developments elsewhere.

What initially seemed like a modest or even negative Net Present Value (NPV) was reinterpreted. It became a measure of financial efficiency. The building’s inflows matched its cost of capital. This indicated that it was performing exactly as expected in a mature market like BGC. Through this shift in perspective, the client gained a clearer understanding of the property’s value. The client also gained a more strategic framework for portfolio management, anchored in data, discipline, and economic logic.

This case highlights how econometric reasoning transforms real estate valuation from a static appraisal into a dynamic decision-making tool. We treated rents, yields, and escalation rates as variables linked to broader economic conditions. This approach helped us uncover not just the property’s value but also the logic behind it. The client learned that a neutral or breakeven NPV is not necessarily a weakness. It can signify equilibrium and maturity in a market. In this market, stability is the new form of strength.

For investors, the key takeaway is that macro-driven valuation brings clarity in times of uncertainty. Understanding how discount rates move with monetary policy provides a sharper sense of timing. Recognizing how escalation aligns with inflation sharpens your understanding of risk and opportunity. For developers, the lesson is strategic. Once a building reaches full occupancy and stable returns, it should be viewed as a core income asset. This asset anchors the portfolio and preserves capital rather than being seen as a speculative venture.

Ultimately, the study demonstrates that data and discipline lead to confidence. In Bonifacio Global City, every percentage point of yield and risk can mean millions in value. Econometric analysis offers a distinct advantage. It gives clients the ability to move beyond intuition. Consultants can also ground their investment strategies on measurable, defensible evidence.

By: AB Agosto, JD, REA, REB, REC, MA Economics (University of San Carlos)
Paralegal – Real Estate, Environmental & Corporate Law

Why Title Annotations and Encumbrances Matter in Property Appraisal

“In valuation, the fine print on the title can be as valuable—or as dangerous—as the land itself.“

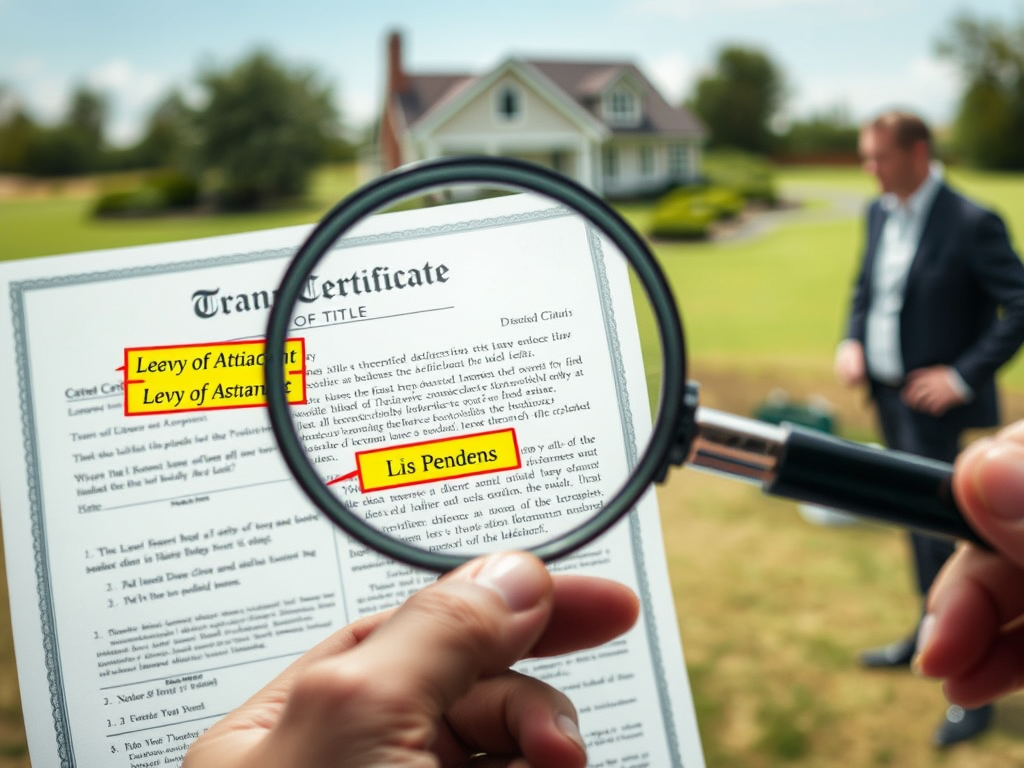
In real estate appraisal, numbers alone do not tell the whole story. A property’s legal status—particularly the annotations and encumbrances appearing on its title or tax declaration—can drastically alter its worth. While some may view these legal markings as mere notarial footnotes, a seasoned property appraiser understands that such entries are crucial to determining the property’s true value, marketability, and risk profile.  One of the most important but sometimes overlooked aspects of valuation is the presence of annotations and encumbrances on the property’s Transfer Certificate of Title (TCT), Original Certificate of Title (OCT), or Tax Declaration. These annotations—whether involving tax delinquency, pending litigation, or other restrictions—can drastically alter a property’s value, marketability, and highest and best use (HBU). For the professional appraiser, understanding and correctly interpreting these legal markings is essential, not optional.

Why Appraisers Must Pay Attention

There are several compelling reasons why a diligent appraiser must care about annotations and encumbrances.

First, these legal burdens directly affect market value—the core product of any appraisal. Buyers in the open market are generally unwilling to pay full price for a property encumbered by unresolved claims, legal disputes, or forfeiture risks. Appraisers must therefore consider how each annotation may cause potential buyers to either walk away or demand a discount.

Second, legal risk translates to value risk. Annotations such as a lis pendens, adverse claim, or a writ of attachment signal potential issues with ownership, possession, or future usability. Even if a property looks physically sound, a legal cloud on its title will make it less attractive and inherently riskier. Prudent appraisers account for this by adjusting their valuation assumptions, often applying a discount or issuing a qualified opinion.

Third, these annotations frequently affect the property’s highest and best use (HBU)—a foundational concept in valuation. If a property is subject to restrictive covenants, reversionary clauses, or foreshore lease limitations, its legal permissibility for development or other productive use may be severely constrained. The appraiser must therefore revise the HBU analysis and its associated value estimate accordingly.

Fourth, annotations impair a property’s marketability. For instance, a property that has been auctioned off for tax delinquency but is still within the redemption period cannot be sold with confidence. Similarly, if a property was inherited but the title transfer is not yet perfected, there may be co-heir disputes or administrative delays. In both cases, the property may be legally transferable only in theory, but not in practice—at least not without cost or time delays.

Fifth, annotations affect the property’s loanable value or equity value. Banks and other financial institutions are wary of lending against titles that carry risks. For example, a property mortgaged beyond its current market value or encumbered with a lien from unpaid taxes may only be eligible for partial financing, or worse, may be rejected altogether as loan collateral. This has direct implications for the appraiser’s task in estimating not just market value, but the net realizable or mortgageable value.

Finally, ignoring these factors may violate the appraiser’s professional and legal responsibilities. Under the Real Estate Service Act (RA 9646), the appraiser is required to exercise due diligence and report all material conditions that affect the value of the property. International Valuation Standards (IVS) and the Uniform Standards of Professional Appraisal Practice (USPAP) similarly require full disclosure and the proper interpretation of legal burdens. Failing to do so may expose the appraiser to liability, loss of license, or reputational damage.

Understanding the Specific Impact of Common Annotations

To make these risks and responsibilities more concrete, let’s examine how common annotations and encumbrances impact valuation:

A Notice of Tax Delinquency or Forfeiture carries a negative impact on value and significantly impairs marketability due to the risk of government seizure. When a Certificate of Sale appears on the title—typically following a tax auction—the buyer only has conditional ownership until the redemption period lapses. This also warrants a discounted valuation and caution in reporting.

A Lis Pendens indicates that the property is subject to ongoing litigation. Its presence severely impairs marketability and imposes legal uncertainty, which in turn reduces value. An Adverse Claim similarly signals a third-party interest in the property that contradicts the titleholder’s claim. While not always litigated, it still creates hesitation for buyers and lenders, pulling values downward.

A Levy or Writ of Attachment represents a judicial restriction. Courts attach the property to secure a possible judgment, and while the property is not yet seized, its transferability is legally curtailed. This justifies a risk adjustment in the valuation.

If the title carries a Foreshore Lease or a Department of Environment and Natural Resources (DENR) annotation, it usually means that the property is within the public domain (such as coastal or reclaimed land). Ownership is limited to leasehold rights, not fee simple. This not only reduces the appraised value to the leasehold interest but also conditions its use based on government regulation.

An Affidavit of Loss or Reconstitution of title temporarily affects the property’s marketability, especially if the reconstitution process is incomplete. Although this may only have a neutral to slightly negative impact on value, it still warrants disclosure and may be included as a limiting condition in the report.

A Real Estate Mortgage (REM), if current and performing, generally has a neutral impact on market value, assuming the appraisal is for market purposes and not equity extraction. However, the appraiser must still distinguish between total market value and the equity portion when applicable.

An Easement or Servitude, such as a right of way or drainage restriction, slightly reduces the value and may condition the property’s utility. If the easement affects buildable area or accessibility, this becomes a material consideration.

Reversion clauses or restrictive covenants are more serious. These limit future development, prohibit certain uses, or allow the property to revert to a former owner under certain conditions. As these significantly constrain HBU and market flexibility, they usually result in a negative value adjustment.

Lastly, annotations involving Deeds of Donation, Inheritance, or Partition may suggest that the property was recently transferred or is part of a co-ownership arrangement. If the legal transfer is incomplete or the estate is unsettled, the title remains in flux. This affects both value and marketability, particularly if there is a risk of future claims or if the sale requires consent from multiple parties.

In real estate valuation, legal clarity is just as important as physical condition. Title annotations and encumbrances represent real risks, limitations, and burdens that influence the value of a property. Whether through discounted sales, delayed transactions, restricted use, or diminished loanability, these legal notations affect how market participants perceive and engage with real estate assets.

The professional appraiser must go beyond mere physical inspection and apply legal awareness, risk sensitivity, and valuation expertise to provide credible, well-supported opinions of value. Every annotation tells a story—of ownership, encumbrance, or uncertainty—and the appraiser must read, interpret, and reflect that story in the appraisal report.

“Work to Learn, Then Earn”: An Appraiser’s Story

An excerpt from an interview with Appraiser Gus Agosto

In this special feature, a Bachelor of Science in Real Estate Management (BSREM) student sits down with Appraiser Gus Agosto to learn about his early journey into the world of real estate appraisal. From his first spark of interest to navigating the challenges of starting, Appraiser Agosto shares how his background in economics, passion for learning, and hands-on experience shaped his professional path. This insightful conversation offers valuable lessons and inspiration for students and aspiring appraisers alike.

Interviewer:

Welcome, Appraiser Gus Agosto. We’re excited to learn more about your journey into the world of real estate valuation. Let’s begin with your early inspiration.

1. What initially drew you to the field of real estate appraisal, and can you recall the moment you decided to pursue it as a career?

Appraiser Gus Agosto:

My journey into appraisal began during my time as a real estate salesperson and property investment specialist. More than a decade has passed since then. One vivid memory stands out: I was in a developer’s office when I met a gentleman who was reviewing for the appraiser’s licensure exam. I watched him work through a complex mathematical problem and admired the analytical skill involved. That moment sparked a deep curiosity in me, one that never left.

Later, during my broker’s review, I began to understand the nuances of the different professions within real estate. Our lecturers were very encouraging, and I gravitated toward appraisal because of its close ties to economics and mathematics—two subjects I’ve always been passionate about. Given my background as a researcher, writer, and a graduate in economics, the transition felt natural. That’s when I firmly decided to pursue a career in real estate appraisal.

2. How did your educational background or early professional experiences prepare you for the demands of property valuation work?

Appraiser Gus Agosto:

I hold a degree in economics and spent several years engaged in research before entering real estate. I conducted studies on local economies, enterprises, and development trends—work that laid the groundwork for the analytical mindset essential in valuation.

My stint as a real estate salesperson further broadened my understanding. I was exposed to different types of properties and transactions, attended seminars, and got to know the real-world workings of the industry. Steve Jobs once said, “You can only connect the dots looking backward.” In my case, those dots connected my work as a researcher, writer, lecturer, and a real estate practitioner, all of which converged toward a solid foundation in appraisal.


3. What challenges did you face when you were just starting out as an appraiser, and how did you overcome them?

Appraiser Gus Agosto:

Like many beginners in the field, I faced the usual questions: Where do I begin? How do I get clients? One piece of advice from a lecturer stuck with me—start with your “KKK”: Kamag-anak, Kliyente, at Kakilala—your natural network. That became my launching pad.

At one professional association event, I met a fellow appraiser who owned an appraisal firm. She invited me to join their Cebu branch, and I accepted without hesitation. It was a valuable opportunity. The company had a structured system, an established client base, and a culture of mentorship. We focused on the core operations—site inspections, analysis, and report writing. Each report we submitted was reviewed by seasoned appraisers, turning every assignment into a learning experience.

Later on, I had the opportunity to work with another appraisal firm in Metro Manila whose clients included major banks and large corporations. There, I learned the discipline of working in a highly coordinated team with tight turnaround times—often just three days per report. The volume of work was intense, but it sharpened my ability to deliver accurate reports under pressure, without compromising quality.

When I returned to Cebu, I reconnected with mentors who were among the pioneering appraisers in Visayas and Mindanao—back when there were only about five of them in the region. They welcomed me into their practice without formal discussions about fees. For me, the priority was learning. I was exposed to a different side of the profession: that of the individual practitioner. Besides Cebu and nearby provinces, I handled assignments even in remote areas such as Kapatagan in Lanao del Norte, Ozamis, and Clarin. I also had the opportunity to appraise properties of prominent Cebuano families and large-scale developments. That phase lasted for at least two years and deepened my understanding of valuation beyond the corporate environment.

Eventually, a batchmate invited me to serve as an appraiser for a nationwide cooperative, marking the start of my independent practice. I traveled to various locations, encountered a wide range of property types and development conditions, met people from all walks of life, and balanced time in the field with desk work in the office. Those routines became the rhythm of my early appraisal career.

In those formative years, I worked with at least three appraisal firms and three respected individual appraisers. My guiding principle was simple: “Work to learn, and earning will follow.” I was driven by a deep eagerness to grow in the profession, more than anything else.

Looking back, my journey—from economic researcher to real estate salesperson to hands-on valuation—was a kind of “gestation period.” Each phase played a vital role in sharpening my skills and shaping my professional identity as a full-fledged appraiser.

4. Looking back at your first appraisal assignment, what lessons did you learn that still guide your practice today?

Appraiser Gus Agosto:

I’ll never forget my first assignment—it was a warehouse in Pagsabungan, Mandaue. My buddy and I were eager and nervous. We did everything manually—measuring the structure, crawling into tight spaces, and sweating through the inspection. It was tough, but also rewarding.

The biggest lesson I learned was about trust. Clients allow us into their private spaces and rely on our judgment to assign value to their property. That responsibility has always stayed with me. I make sure to explain to my clients how I arrived at the valuation and why it’s fair. For me, valuation is not just about figures—it’s about credibility, integrity, and professionalism. Trust is the foundation of our practice, and I continue to uphold that principle in every report I sign.

Advice to Aspiring Appraisers:

Appraiser Gus Agosto:

To those just starting: “Work to learn first, not just to earn.” Be open to guidance, surround yourself with mentors, and never stop asking questions. This profession is built not just on numbers, but on experience, trust, and continuous growth. Stay curious, stay humble, and stay committed.

Interviewer Wrap-Up:
Thank you, Appraiser Gus Agosto, for that inspiring and grounded look into your journey. Your story is not only a blueprint for aspiring appraisers but also a testament to how passion, persistence, and purpose can shape a meaningful career.

The Essential Role of Master Planning in Real Estate

Clients often want to explore what their properties can become, not just what they are worth today. Potential encompasses the possible future uses and developments that can enhance the value and utility of the property. Through master planning, we analyze various factors such as location, market trends, demographic shifts, and regional growth patterns to identify opportunities for development and improvement.

Maximal use refers to optimizing the utilization of a property to achieve its highest and best use. This involves detailed planning and strategic decision-making to ensure that the property is developed in a way that maximizes its value, functionality, and sustainability. We consider various scenarios and use cases, from residential and commercial developments to mixed-use projects, ensuring that every square meter of the property is used effectively.

In contrast to conventional master plans focused narrowly on technical and physical aspects, our approach is more expansive and inclusive. We go beyond traditional boundaries of architecture and engineering to incorporate rigorous analyses of market trends, legal, economic feasibility, environmental sustainability, and comprehensive risk management. This broader perspective ensures that our projects are not only viable but also resilient and adaptive to changing environments and challenges.

The Role of Master Planning

Our master planning services begin with a thorough analysis of the property, including its legal and physical characteristics, existing infrastructure, and environmental conditions. We also conduct market and feasibility studies to understand the economic viability of potential developments. This comprehensive analysis forms the foundation of our master plans, ensuring they are grounded in reality and aligned with market demands.

Master planning is about creating a strategic vision for the property’s future. We collaborate with our clients to understand their goals and aspirations, integrating their vision into the master plan. This strategic approach ensures that the plan not only addresses immediate needs but also sets a course for long-term growth and development.

Market Analysis

Market analysis is a cornerstone of effective master planning in real estate, providing essential insights into market trends, demand-supply dynamics, and consumer behavior. By conducting thorough analyses, master planners can identify opportunities, mitigate risks, and optimize strategies to enhance project feasibility and long-term success. Integrating market insights ensures that developments are not only responsive to current market conditions but also positioned for sustainable growth and resilience in the future.

Financial Analysis

Financial viability is a cornerstone of successful master planning. We conduct detailed financial analyses to assess the feasibility of proposed developments. This includes market analysis, financial modelling, cost estimation, revenue projections, and return on investment calculations. By evaluating the financial aspects thoroughly, we help clients make informed decisions and attract potential investors.

Economic Impact

Master planning also considers the broader economic impact of development projects. Economic analysis in real estate and investment decisions involves several key tools and techniques that guide investors and developers in making informed choices. We analyze how proposed developments can stimulate local economies, create job opportunities, and attract businesses and investments. This holistic view ensures that the development contributes positively to the economic vitality of the region.

Environmental Sustainability

Sustainable development is at the core of our planning process. We conduct comprehensive environmental impact assessments to understand and mitigate the ecological footprint of developments. This includes evaluating potential impacts on air and water quality, natural habitats, and biodiversity. Our plans incorporate green building practices, energy efficiency measures, and renewable energy solutions to minimize environmental impact.

Our master plans emphasize the integration of green spaces, parks, and recreational areas to enhance the quality of life for residents and promote environmental sustainability. These spaces not only provide aesthetic and health benefits but also contribute to the ecological balance of the area.

Legal and Regulatory Compliance

Legal due diligence and proactive management of ownership and legal barriers are integral to effective master planning in real estate. By verifying ownership, identifying legal barriers, and ensuring regulatory compliance, we mitigate risks, enhance project feasibility, and facilitate smooth implementation. We also ensure that all projects comply with local, regional, and national regulations. This includes zoning laws, building codes, environmental regulations, and land use policies. This proactive approach enhances project feasibility, mitigates risks, and facilitates smooth implementation

Risk management is integral to our master planning approach. We identify potential legal, financial, and environmental risks and develop strategies to mitigate them. This proactive approach ensures the long-term success and sustainability of our projects.

Conclusion

Our clients look to us for more than just property valuations; they seek insights into the potential and maximal use of their properties. Through our comprehensive master planning services, we provide the strategic vision, detailed analysis, and innovative solutions needed to unlock that potential and maximize use. By integrating financial viability, economic impact, environmental sustainability, and legal compliance, we ensure that our projects are sustainable, resilient, and successful.

This holistic approach not only enhances the value of the property but also ensures balanced growth that preserves natural resources, promotes community well-being, and fosters long-term economic vitality. Our expertise in master planning positions us to lead in nurturing and developing thriving communities that stand the test of time.