AI in Real Estate Appraisal:Does AI Change the Rule?

Artificial intelligence is moving into the real estate appraisal profession fast. At seminars, conferences, and professional discussions, appraisers are increasingly being encouraged to bring ChatGPT and other AI tools into their work.

There’s nothing wrong with that on its own. Used well, AI can be a genuinely useful tool for appraisers.

The trouble starts when AI is pitched as something you can simply ask to determine a property’s value — sometimes without even inspecting the property. That proposition deserves closer scrutiny.

AI Does Not “Know” Property Value

Ask an AI system for a property’s value and it will often produce an estimate readily — one that can look remarkably precise.

But where did that number come from?

Market value isn’t information AI inherently possesses. A credible opinion of value has to be supported by relevant market evidence, and AI is only as useful as the information it has to draw on.

This matters most in markets where reliable transaction data is thin. Where actual selling prices, property characteristics, transaction dates, and similar information are publicly available and systematically recorded, automated valuation systems have a lot to work with. Where that information is fragmented, privately held, hard to verify, or simply unavailable, the picture changes completely.

Online listings may be abundant, but an asking price is not a transaction price. A property listed at ₱20 million may eventually sell for ₱16 million. Another may never sell at all. A transaction may involve unusual financing, related parties, package deals, distress, or other conditions that never make it into the listing.

An AI system that doesn’t know any of this can still produce a confident-sounding estimate. That’s exactly where the danger lies.

Precision Is Not the Same as Reliability

Suppose an AI system concludes that a parcel of land is worth ₱18,437 per square meter. The figure looks scientific because it’s precise.

But suppose the data behind it consists mostly of asking prices, duplicated listings, outdated postings, mislocated properties, and transactions whose actual consideration was never verified.

No amount of sophistication in the calculation can make up for weak evidence underneath it. Worth remembering:

Precision of output is not reliability of value.

A sophisticated algorithm run on unreliable information just produces a sophisticated-looking but unreliable conclusion. Garbage in, garbage out didn’t go away because AI showed up.

ChatGPT Is Not an Automated Valuation Model

This distinction gets missed constantly.

ChatGPT and similar generative AI tools are general-purpose systems, built to understand, organize, analyze, and generate information. An Automated Valuation Model (AVM), by contrast, is purpose-built to estimate property values using defined property databases, transaction data, statistical techniques, and valuation models.

They are not the same thing.

Even a well-designed AVM has limits — its reliability depends heavily on the quantity, quality, recency, and representativeness of its underlying data. If a specialized valuation model struggles when market information is inadequate, there’s even more reason for caution when a general-purpose AI system is asked to value a specific property without being handed sufficient, reliable evidence to work from.

AI can process information. It cannot manufacture reliable market evidence where none exists.

Can AI Replace Property Inspection?

An equally concerning idea is that AI has made physical inspection unnecessary.

There may be legitimate cases for desktop or limited-scope valuation, depending on the applicable standards, the purpose of the assignment, the evidence available, and the agreed scope of work. But that’s a very different claim from saying AI removes the need for inspection altogether.

Consider what an appraiser actually finds on-site that no database captures reliably:

  • actual road access and road width
  • topography and elevation
  • physical condition of improvements
  • neighborhood influences
  • encroachments, easements, and rights-of-way
  • flooding or drainage conditions
  • transmission lines and other infrastructure
  • actual frontage
  • surrounding land uses
  • quality of views
  • occupancy
  • inconsistencies between documents and actual conditions
  • other physical characteristics affecting utility and marketability

A database may show a property fronting a road. Inspection may reveal the “access” is a narrow passage shared with several other lots. A map may show a regular, developable parcel. Inspection may reveal severe topographical limitations. Records may describe a residential improvement in good condition. Inspection may reveal serious deterioration.

AI cannot analyze a property characteristic it was never given. Technology doesn’t eliminate the need to actually understand the property being valued.

AI Cannot Cure Inadequate Appraisal Evidence

This may be the single most important idea in the whole discussion: AI cannot cure inadequate appraisal evidence.

Technology can process evidence faster. It can surface relationships within that evidence. It can organize thousands of data points at once. What it cannot do is turn unreliable information into reliable market evidence just by running it through a model.

The difference plays out like this:

  • AI + poor data + no verification + no appropriate inspection → a potentially misleading estimate
  • AI + reliable data + professional verification → genuinely useful analytical assistance
  • AI + reliable data + appropriate inspection + sound methodology + professional judgment → powerful appraisal support

The difference isn’t the sophistication of the AI. It’s the quality of the appraisal process around it.

Can AI Apply the Correct Valuation Method?

Even with sufficient data, another question remains: can AI determine the appropriate method for valuing a given property?

AI can certainly run the calculations. Given verified comparable sales, transaction dates, property characteristics, and defensible adjustments, it can assist with the Sales Comparison Approach — computing unit values, applying adjustments, analyzing ranges, testing alternative assumptions. Given reliable rents, vacancy rates, operating expenses, capitalization rates, and growth assumptions, it can run the Income Approach, including capitalization and discounted cash-flow analysis. Given reliable land values, construction costs, depreciation, and obsolescence data, it can assist with the Cost Approach.

But performing a method correctly is not the same as selecting the right method. That distinction is fundamental.

A Correct Calculation Can Still Produce the Wrong Appraisal

Take a beachfront resort property. An AI system might pull nearby land listings, calculate price per square meter, apply mathematical adjustments, and produce an indicated value — flawlessly.

But what if buyers of comparable resort properties actually base their decisions on income-generating capacity, development potential, tourism demand, or redevelopment opportunity, not raw land comparables? The math can be correct while the underlying methodology is entirely wrong for the asset.

The same trap applies to hotels, industrial properties, special-purpose properties, leasehold interests, partial takings, landlocked parcels, properties burdened by transmission-line easements, environmentally constrained sites, and properties with significant redevelopment potential.

AI can calculate almost anything. The professional question is whether that’s what should have been calculated in the first place. A correct calculation using the wrong valuation method is still a wrong appraisal.

Highest and Best Use Comes Before the Method

There’s a deeper layer still. Before an appraiser even selects a valuation approach, they must determine the property’s highest and best use.

A vacant parcel might physically resemble the residential lots around it. But its zoning, accessibility, location, development trends, physical characteristics, and market demand may point to an entirely different use. Get the highest and best use wrong, and everything downstream can be technically sophisticated and still conceptually wrong.

The proper sequence looks like this:

  1. Identify the property and property rights
  2. Define the appraisal assignment and valuation date
  3. Inspect and investigate as appropriate
  4. Analyze physical, legal, economic, and market characteristics
  5. Determine highest and best use
  6. Select the appropriate valuation approach and method
  7. Apply relevant, verified market evidence
  8. Reconcile the value indications
  9. Form the opinion of value

AI can assist at nearly every one of these stages. But if the whole process starts and ends with a single prompt — “What is the value of this property?” — most of the essential valuation questions never actually get answered.

AI May Spot Similarity — The Appraiser Determines Comparability

Comparable-property analysis is a good illustration of where AI genuinely helps and where it can’t take over.

Given enough reliable data, AI can screen hundreds or thousands of properties and flag those that look statistically similar to the subject. That’s valuable. But statistical similarity is not the same as appraisal comparability.

Two properties can have nearly identical lot areas and sit a short distance apart, yet differ substantially because one has better road access, wider frontage, superior topography, a better view, flood exposure, a transmission-line easement, development restrictions, stronger commercial exposure, or a different highest and best use altogether.

AI may identify statistical similarity; the appraiser determines comparability. Selecting comparables isn’t a search for similar numbers — it requires understanding which characteristics actually drive buyer and seller behavior in that specific market.

Where AI Can Truly Help

None of this means appraisers should reject AI. Quite the opposite — they should learn to use it well.

AI can help organize large datasets, screen potential comparables, analyze market trends, review documents, summarize regulations, flag inconsistencies, run statistical analyses, prepare sensitivity tests, work through income and expense figures, check calculations, and sharpen the clarity and consistency of appraisal reports. It can cut the time spent on repetitive work dramatically.

It’s also an effective quality-control tool — spotting inconsistencies between sections of a report, stress-testing assumptions, checking math, comparing scenarios, and flagging items that need further investigation.

Used well, AI frees the appraiser to spend more time where professional expertise actually matters most: verification, interpretation, highest and best use, methodology, comparability, reconciliation, and judgment. The right relationship looks like this:

AI assists → the appraiser verifies → the appraiser analyzes → the appraiser judges → the appraiser takes responsibility.

The Appraiser Still Signs the Report

This point shouldn’t get lost in the enthusiasm.

If an appraisal contains an unsupported adjustment, an inappropriate comparable, a wrong assumption, the wrong valuation method, or a flawed conclusion, the appraiser cannot fall back on “the AI generated it.” The professional who adopts the analysis and signs the report remains accountable for the opinion of value.

Artificial intelligence does not assume professional accountability. The appraiser does.

The Wrong Question About AI and Appraisal

The debate shouldn’t really be whether AI can produce a property value. Of course it can — a calculator can produce a number, a spreadsheet can produce a number, a regression model can produce a number, an AVM can produce a number, and so can ChatGPT.

The question that actually matters is: can the appraiser demonstrate that the resulting opinion of value is supported by sufficient, relevant, verified market evidence, appropriate methodology, and sound professional judgment?

That’s what separates a numerical estimate from a defensible professional appraisal.

AI Will Change Appraisal — Not Its Foundations

AI is going to reshape this profession. Data gathering will get faster. Market databases will get more sophisticated. Comparable searches will become increasingly automated. Statistical analysis will become accessible to far more practitioners. Report preparation and quality control will get dramatically more efficient. All of that is worth welcoming.

But the fundamentals of valuation don’t move. The appraiser still has to understand the property. Still has to understand the market. The evidence still has to be relevant, and the data still has to be verified. Highest and best use still has to be analyzed. The methodology still has to be appropriate. The conclusion still has to make economic sense. And someone still has to exercise professional judgment and take responsibility for the resulting opinion.

So the better message to appraisers isn’t “use AI to determine property value.” It’s this: use AI to strengthen the appraisal process, but never let it substitute for the evidence, verification, appropriate inspection, methodology, market analysis, and professional judgment an opinion of value actually depends on.

The future of appraisal isn’t AI versus the appraiser. It belongs to the appraiser who knows how to use AI effectively — and just as importantly, knows its limits and when its output shouldn’t be trusted.

Because the challenge in appraisal has never really been producing a number. It’s being able to explain and defend why that number represents value.
Evidence-Based Valuation: Reconciling Property, Planning, Economic, and Market Evidence

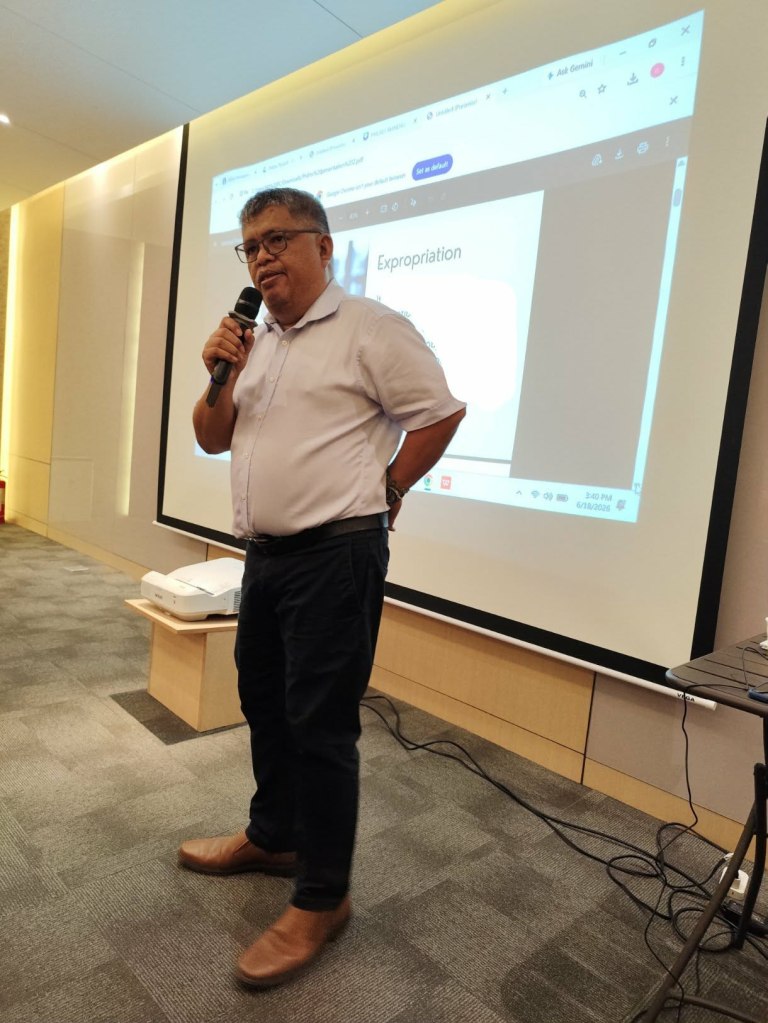
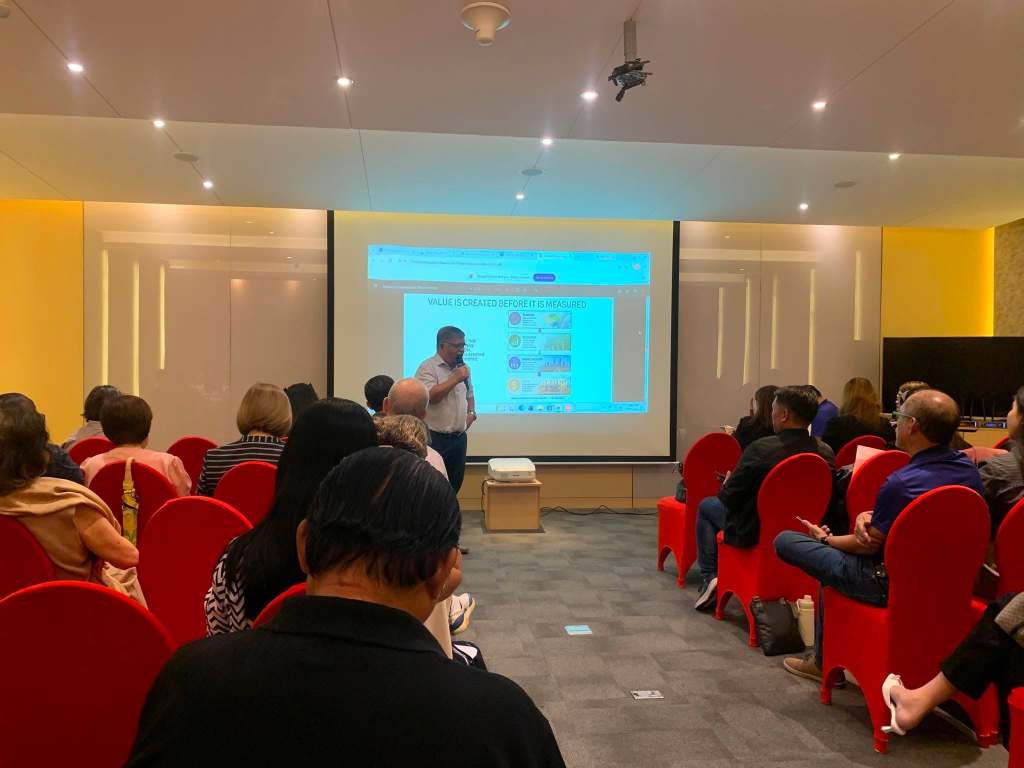
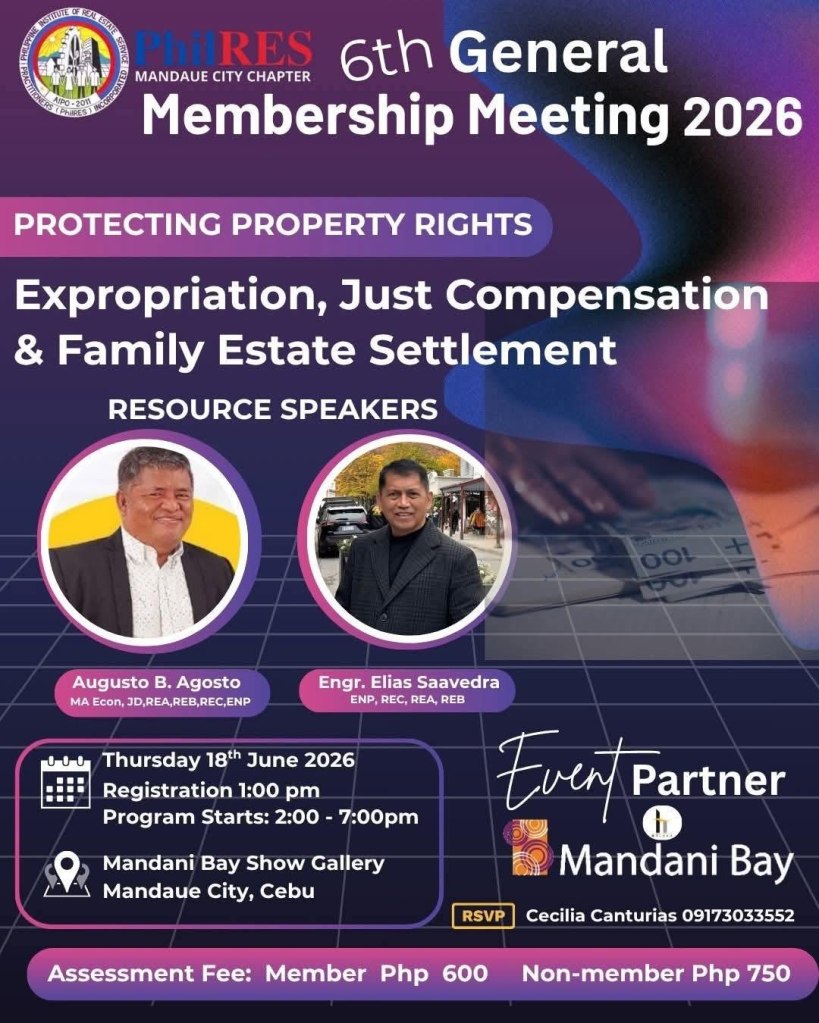
On June 18, 2026, I had the privilege of speaking before the members of the Philippine Real Estate Service Practitioners, Inc. (PhilRES) – Mandaue City Chapter during its 6th General Membership Meeting held at Mandani Bay, Mandaue City. My presentation focused on a subject that has occupied much of my professional work in recent years: Evidence-Based Valuation (EBV) for Litigation, Expropriation, and Just Compensation.

For decades, real estate valuation has relied heavily on the Sales Comparison Approach. Comparable sales remain an important source of market evidence and continue to be one of the most widely accepted methods of determining value. However, in many assignments—particularly expropriation cases, litigation matters, infrastructure projects, and complex property disputes—the question often arises: Is market evidence alone sufficient to explain value?

The traditional appraisal process frequently emphasizes numerical adjustments derived from comparable transactions. While mathematically sound, such an approach may not fully capture the broader factors that influence value. Infrastructure investments, zoning regulations, land use policies, economic growth, scarcity, accessibility, environmental conditions, and development potential all contribute to the creation of value long before they are reflected in actual market transactions.

This observation led to the development of a framework I refer to as Evidence-Based Valuation (EBV).

The central premise of EBV is straightforward: value conclusions should not rely solely on comparable sales but should be supported by the reconciliation of multiple forms of evidence. These include:

Property Evidence – the physical characteristics of the property such as location, area, shape, topography, accessibility, improvements, and development potential.

Planning Evidence – land use plans, zoning classifications, infrastructure projects, government policies, and regulatory controls that influence future utility and development.

Economic Evidence – demand and supply conditions, growth trends, scarcity, investment activity, income potential, and broader economic drivers.

Market Evidence – comparable sales, listings, market transactions, and investor behavior.

These forms of evidence are not independent of one another. Rather, they interact to influence the highest and best use of a property, which ultimately forms the basis of value.

The concept is equally relevant in both ordinary valuation assignments and special-purpose engagements. Evidence-Based Valuation strengthens the foundation of value conclusions by integrating multiple forms of evidence beyond comparable sales alone. Even in ordinary market valuations, appraisers are expected to provide conclusions that are not only supported by comparable sales but also grounded in a thorough understanding of the property’s characteristics, planning context, and economic environment. Courts are often asked to determine compensation that is fair not only to the government but also to the property owner. In such situations, the challenge is not merely selecting a comparable sale but reconciling all available evidence to arrive at a value conclusion that is credible, transparent, and defensible.

Evidence-Based Valuation does not seek to replace established valuation approaches. Instead, it seeks to strengthen them by expanding the evidentiary foundation upon which value conclusions are formed. Comparable sales remain important, but they should be viewed as one component of a broader evidentiary framework rather than the sole determinant of value.

As valuation professionals, we are increasingly called upon to explain not only what a property is worth, but also why it is worth that amount. This requires a deeper examination of the factors that create, sustain, and influence value.

The EBV framework remains a continuing work in progress. Future developments will explore its application to litigation valuation, water rights valuation, infrastructure projects, feasibility studies, market analysis, and just compensation determinations. The objective is not to create complexity for its own sake, but to improve transparency, strengthen professional judgment, and provide decision-makers with more defensible valuation conclusions.

Ultimately, valuation is not merely a mathematical exercise. It is the process of evaluating evidence, reconciling competing perspectives, and arriving at a reasoned conclusion. In that sense, evidence is not an alternative to valuation—it is the foundation upon which valuation rests.

Value is created before it is measured.

Monterrazas and the Tragedy of the Commons

Why System Thinking Requires Stricter Development Standards

Recent public discussions have reflected different perspectives on the Monterrazas development in Cebu City, including system-level explanations, precautionary considerations, and calls for regulatory review. These illustrate the complexity of decision-making in such contexts.

At first glance, the issue may appear as a familiar tension between development and environmental protection. However, it may be more accurately understood through a different lens.

From an economic perspective, what this situation reflects is a form of the Tragedy of the Commons.

The concern lies in understanding how multiple developments interact within a shared system, and how each contributes to cumulative impacts over time.

Cebu’s upland areas perform essential ecological functions. They absorb rainfall, regulate runoff, and contribute to the stability of downstream communities. These functions do not operate within the boundaries of individual properties. They extend across space, linking different parts of the city through continuous hydrological processes.

In this context, the question of whether a particular development lies within or outside a defined watershed boundary, while relevant in technical terms, does not fully resolve the issue. Environmental systems do not operate as isolated compartments. Their behavior reflects interaction rather than separation.

The scale of that interaction is often difficult to grasp in abstract terms.

Evidence from watersheds within Metro Cebu further clarifies how this system operates—and how development must be understood within it.

Studies of the Mananga watershed show that land-use and land-cover changes—particularly in upstream areas—affect infiltration, surface runoff, and the movement of water across the system. As vegetation is reduced or land is altered, less water is absorbed and more becomes surface flow.

A similar pattern is observed in the Butuanon River watershed. The river originates in upland areas of Cebu City and flows through increasingly urbanized zones before reaching the coast. Upstream areas are already characterized by agricultural and altered land uses, while downstream sections are densely developed. This configuration illustrates how water accumulates as it moves across elevations, shaped by both upstream conditions and downstream constraints.

Altogether, these cases point to a consistent principle:

The watershed is the system within which individual projects must be considered, as runoff is generated across the entire catchment while its behavior is shaped by land-use conditions across different elevations.

This framing is critical. It does not assign causation to any single location. Rather, it defines the proper unit of analysis.

A project is not evaluated in isolation, but in relation to the system it enters—where each intervention contributes to cumulative pressures and must therefore be assessed with reference to the system’s capacity.

It is often observed that flooding in Cebu is multi-causal. Infrastructure limitations, watershed conditions, land-use changes, and rainfall patterns all contribute. This observation is correct.

However, its implication must be properly understood.

If multi-causality is interpreted to mean that no single development can be meaningfully evaluated, then responsibility becomes diffused. Multiple factors contribute, yet accountability becomes less clearly defined.

But the correct implication is the opposite.

If risk is systemic, then evaluation must also be systemic—and correspondingly more rigorous.

The system is not an excuse—it is the basis for stricter evaluation.

This requires a shift in how development decisions are made.

The relevant question is not whether a particular project can be shown to cause a specific flooding event. Rather, it is whether the addition of that project contributes, in combination with others, to increasing pressure on a system that may already be approaching its limits.

The concern lies in the combined effects within a shared system, and in how each individual project contributes to those cumulative impacts.

This leads to a central question:

What is the capacity of the system?

How many developments are already present within a given environmental zone?
To what extent has land use already been altered?
At what point does additional development begin to significantly affect the system’s ability to absorb rainfall and regulate runoff?

Without a clear understanding of these limits, development decisions are made incrementally, without reference to cumulative thresholds.

The Monterrazas issue, therefore, should be viewed in terms of how development decisions are made when each additional project contributes to a system with finite capacity.

In such a context, compliance at the project level is no longer sufficient. Each additional intervention must be evaluated in relation to the condition of the system as a whole.

This has significant implications for urban development.

First, evaluation must move beyond individual projects toward system-level analysis.

Second, development must be aligned with capacity. Growth is no longer simply a matter of feasibility or compliance, but of whether the system can sustain additional pressure.

Third, planning must shift from reactive to anticipatory. Addressing impacts only after they occur is both inefficient and costly.

Fourth, institutional coordination must ensure that decisions reflect a consistent understanding of cumulative risk.

The Monterrazas issue is not resolved by determining whether it falls within a particular boundary, nor by isolating it from broader conditions.

It must be understood as part of a system where effects accumulate, capacity is finite, and each development contributes to increasing pressure on that system.

It shows that outcomes in shared systems are shaped not only by individual decisions, but by how those decisions accumulate—and whether they are governed by a clear understanding of limits.

Ultimately, the question is not whether a particular project should proceed or not.

It is whether each project is evaluated in light of the system it enters—and whether that system can sustain the additional burden it brings.

Because in such systems, urban development is no longer simply about what can be built.

It is about how each development contributes to a shared environment—and whether the whole remains within its capacity to endure.

Why Effective Report Writing Adds Value

In the practice of real estate appraisal, much emphasis is often placed on the technical process of valuation—data collection, market analysis, and the application of valuation approaches. However, as Mr. Gus Agosto emphasized in a recent lecture on Appraisal Report Writing, one of the most overlooked yet indispensable components of the appraisal process is the ability to clearly and effectively communicate its outcome. Effective appraisal, as he asserts, means effective reporting.

Drawing from over a decade of experience in the field, Mr. Agosto highlighted that writing an appraisal report is not merely a clerical task or an afterthought to technical valuation. It is the final product—the formal articulation of an appraiser’s professional opinion of value. This report must not only present data but must also comply with standards, reflect sound judgment, and demonstrate adherence to the legal and ethical expectations of the profession.

Some appraisal reports currently in circulation—particularly those used as templates—were created prior to the passage of Republic Act No. 9646, known as the Real Estate Service Act of the Philippines (RESA Law). Others are adapted from international formats that may not fully conform to Philippine legal and regulatory requirements. While these templates may serve as useful starting points, Mr. Agosto stressed that they are insufficient if not updated to reflect local laws and contemporary standards. Over the past decade, numerous laws and administrative issuances have been enacted, including the Philippine Valuation Standards (PVS), Data Privacy Act, Electronic Commerce Act, Anti-Money Laundering Act, updates to BIR Revenue Regulations, and court procedural rules, which must now be reflected in appraisal report writing.

Under Section 3(g) of the RESA Law, a real estate appraiser is legally defined as a professional who “performs or renders, or offers to perform services in estimating and arriving at an opinion of or acts as an expert on real estate values,” and whose services “shall be finally rendered by the preparation of the report in acceptable written form.” This statutory requirement emphasizes that the report is not a mere formality; it is the legal expression of the appraiser’s findings and professional responsibility.

Further, Section 5(c) of the Implementing Rules and Regulations (IRR) of R.A. 9646 mandates that licensed appraisers shall “prepare, sign, and issue a real estate appraisal report” in accordance with accepted principles and standards prescribed by the Board and the Professional Regulation Commission (PRC). The PVS, aligns with the International Valuation Standards (IVS) but is tailored to Philippine law and practice. Reports must demonstrate transparency in methodology, accuracy in assumptions, and consistency in legal compliance.

Mr. Agosto also pointed out that appraisal reports are not generic in nature. They must be purpose-specific, as each type of valuation engagement—litigation, insurance, sales, taxation, lease, or expropriation—carries distinct reporting requirements, legal standards, and evidentiary burdens. Moreover, Mr. Agosto emphasized that the appraiser’s ability to communicate effectively, through proper grammar, structure, and clarity, is just as important as analytical rigor. A report written in poor language or filled with jargon may undermine its credibility, even if technically correct. Thus, he encourages appraisers to continually upskill in both technical and language proficiency, utilize digital tools, apply peer review, and align with style guides that enhance report readability and presentation.

Appraisal reports serve as vital documents in court cases, bank financing, taxation, and public policy. Thus, Mr. Agosto explained, they must be credible, compliant, and defensible. This requires not only legal and technical knowledge, but also proficiency in professional communication. The appraiser must be able to clearly convey complex data, defend conclusions logically, and eliminate ambiguity through proper grammar, sentence structure, and vocabulary. In an era where reports are often read by legal, financial, and lay audiences alike, the precision and clarity of language can determine whether the report is useful—or even admissible.

Hence, appraisal report writing is not just a skill—it is a professional obligation grounded in law, ethics, and service to the public good. It transforms raw valuation data into a structured, credible, and actionable opinion of value. As Mr. Agosto aptly concluded: “Your report is your professional signature. It must speak with competence, integrity, and purpose long after you’ve signed it.”