From Measuring Property to Understanding Value: The Economics Every Appraiser Should See

I once had a conversation with a colleague who remarked that appraisers should know how to measure property. I agree completely — measurement is fundamental to appraisal practice. We measure land, frontage, road width, floor area, improvements, setbacks, distances. It’s probably why appraisers so often feature their measuring wheels and laser meters when documenting an inspection.

There’s nothing wrong with that. An appraiser should understand the property being valued, and accurate physical data is part of that job.

But the conversation led me to a more fundamental question: after we’ve measured the property, do we already understand its value?

A measuring wheel can tell us the length of a road. A laser meter can give us the dimensions of a building. A survey can establish the boundaries and area of land. But none of these instruments can explain why one square meter is worth more than another. That question takes us beyond measurement and into economics.

The appraiser has to see property in two dimensions at once: as a physical asset that can be identified and measured, and as an economic asset whose value comes from utility, scarcity, rights, location, market demand, cost, time, and risk. What follows are several angles on that same idea — some familiar terrain (frontage, location, zoning), some less obvious (a 455-square-meter access parcel with an outsized economic role).

Property Has Both a Physical and an Economic Dimension

Consider two parcels, each exactly 10,000 square meters. By measurement, they contain the same quantity of land. But suppose one is remote with difficult access, while the other fronts a major highway near an expanding commercial district. The physical quantity is identical. The economic possibilities are not — better accessibility, greater exposure, lower transport costs, a larger addressable market.

Measurement tells us how much property exists. Economics tells us what that property can do. Recording physical characteristics is only the starting point; the real task is working out the economic consequences of those characteristics.

Measurement Is Essential, but It Is Only the Beginning

Suppose an appraiser establishes that a parcel contains exactly 10,000 square meters. That’s an important physical fact. But consider four properties, each containing exactly 10,000 square meters. One is agricultural land with limited road access. Another fronts a major commercial highway. A third lies within an area designated for tourism development. A fourth sits inside an emerging industrial corridor.

Their land areas are identical. Their economic characteristics are not. The market may see entirely different opportunities, limitations, costs, risks, and potential benefits in each one.
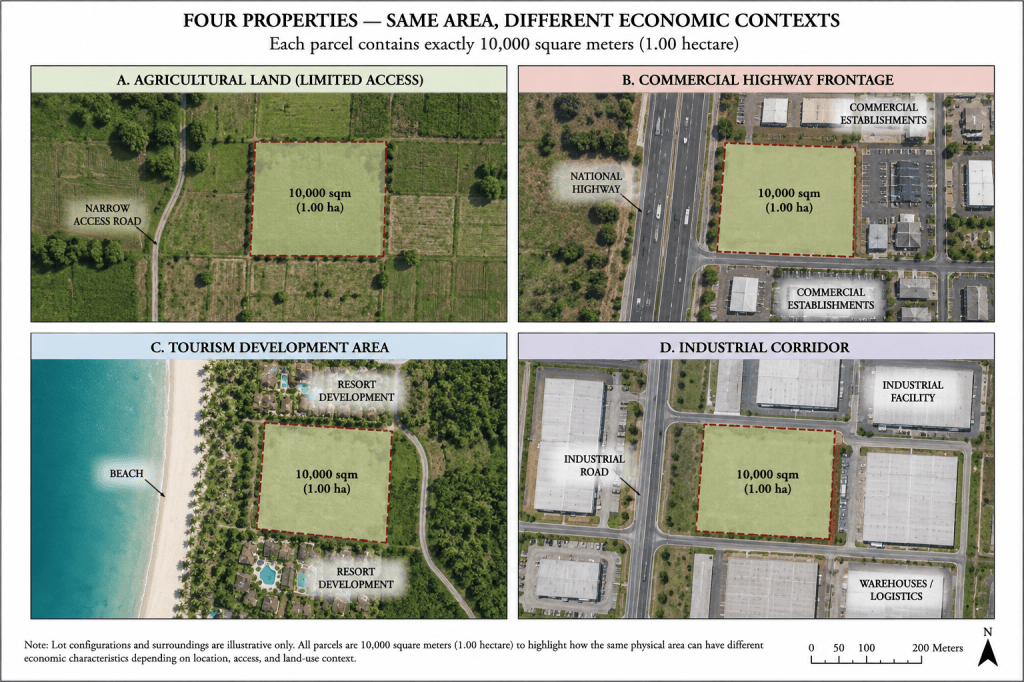
Figure 1. Four illustrative 10,000-square-meter parcels demonstrating how identical physical land areas may possess different economic characteristics because of differences in accessibility, surrounding development, land-use context, market opportunities, and potential utility.

Measurement establishes the physical quantity of property. Valuation has to explain its economic significance. So the appraiser’s work can’t end with area, frontage, shape, topography, floor area, or construction characteristics — those physical facts still need to be connected to their effects on utility, marketability, development potential, income, cost, risk, and market behavior.

From Physical Characteristics to Economic Consequences

Take frontage. An appraiser can establish that a parcel has 100 meters of road frontage — that’s a physical measurement. But the valuation question goes further: Does the frontage provide better visibility? Does it allow multiple access points? Does it facilitate subdivision? Does it improve commercial exposure? Does it reduce the cost of internal circulation? And, ultimately, does the market actually recognize and pay for those advantages?

The same reasoning applies to topography. A steeply sloping property may require substantial site-development expenditure and yield less usable area — a real economic disadvantage. But in another market, that same elevation might provide views that make a resort or residential development more attractive, not less. The physical characteristic is identical in kind (a slope); its economic consequence depends entirely on context.

Physical Characteristic → Economic Consequence → Market Response → Value

This is where economics starts giving meaning to physical property.

Location Is an Economic Relationship

“Location, location, location” gets repeated so often it’s easy to forget what actually makes location valuable. Location isn’t a coordinate on a map — its value comes from relationships: proximity to employment centers, a nearby port, a highway, a tourism corridor, a hospital, a population center.

What we call a “location advantage” is really a bundle of underlying benefits — lower transport costs, accessibility, access to larger markets, proximity to jobs, agglomeration effects, development opportunity. So the appraiser’s question isn’t just where is the property — it’s what relationships does this location create, and how do they affect utility and market behavior?

Access as Economic Infrastructure
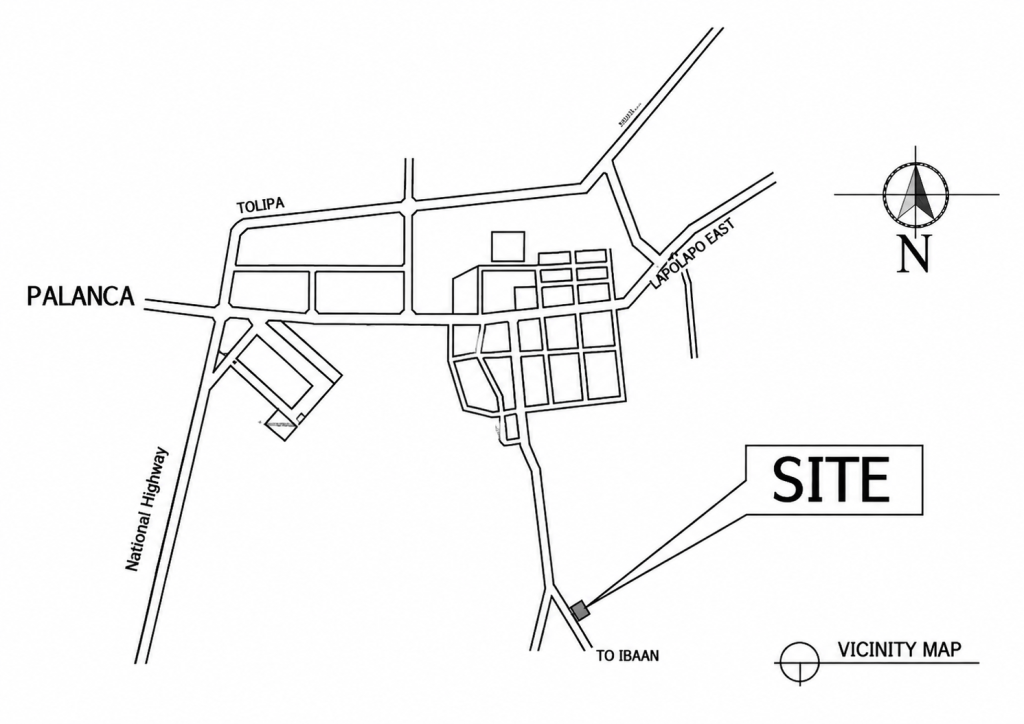
Figure 2. Vicinity map illustrating the relationship between the subject property, the surrounding road network, and established areas of development. Source: appraisal working file.

A vicinity map looks like a purely physical document — it shows where the site sits relative to roads and surrounding development. But it raises economic questions, not just locational ones. Does the road connect the property to markets or population centers? Does it lower transport costs, enable development, provide commercial exposure? Is its capacity adequate? Are there alternative routes, and at what cost?

At first glance, the map is simply a physical representation of location. It identifies the subject site and shows its relationship to surrounding roads and nearby developed areas. For valuation purposes, however, it contains more than locational information — it raises economic questions.

The appraiser shouldn’t stop at measuring the property’s distance from a road or the width of an access route. The more important inquiry is what that access means to the property’s economic utility. The map may prompt the appraiser to investigate whether the property has direct, legally available access; the quality and capacity of the connecting road; its relationship to established population or commercial centers; the cost of improving access; alternative routes; travel time; and whether existing access is sufficient to support the property’s highest and best use.

A road isn’t significant merely because it has a measurable width and length. Its valuation significance comes from what it enables — improved accessibility, lower transportation costs, development feasibility, connection to markets and population centers, or turning an otherwise underutilized property into an economically viable one.

Physical Access → Connectivity → Economic Utility → Development Feasibility → Market Response → Value

This distinction matters even more when access depends on a relatively small parcel of land. If that parcel is the practical connection between a much larger property and the existing road network, its economic significance can’t necessarily be understood by simply multiplying its area by the prevailing price per square meter. The appraiser has to investigate its function within the larger property system — not just its size.

That said, this doesn’t mean the access parcel automatically captures the entire value it helps create in the larger property. Alternative routes, legal rights of access, development costs, road standards, planning requirements, and market evidence still need to be examined on their own terms.

The point stands either way: measurement identifies the physical characteristic; valuation investigates its economic consequence.

When a Small Parcel Has a Larger Economic Function

This becomes especially clear when a small parcel provides the practical connection to a much larger property. Suppose an access parcel is only 455 square meters, but it controls access to a 13,000-square-meter property behind it.

If the analysis stays purely physical, it collapses into:

455 sqm × unit value per sqm = indicated value

That’s mathematically simple — and economically incomplete. The real question isn’t “what are 455 square meters worth,” it’s “what economic opportunity does access through these 455 square meters create or facilitate?” The smaller parcel can shape accessibility, development efficiency, marketability, and ultimately the productivity of the much larger property behind it.

That doesn’t mean the access parcel automatically captures all the value it enables — that would require its own separate analysis of alternative routes, legal access rights, development costs, and market behavior. But it illustrates a broader principle: the economic significance of land isn’t necessarily proportional to its physical size. A small parcel can perform an outsized economic function. The measuring wheel gives you its dimensions; economics explains its contribution.

Zoning and the Economic Opportunity Set

Suppose agricultural land becomes eligible for tourism development. Physically, nothing changes — same area, same boundaries, same topography. But something economically significant has shifted: the range of legally permissible uses. Buyers might now consider accommodation, recreation, agritourism, restaurants, resorts, events.

Property Rights → Permissible Uses → Economic Opportunities → Expected Benefits → Market Expectations → Value

One important qualification must be made. Legal permission does not automatically translate into economic value. However, a change from an agricultural classification to one that permits tourism development can materially expand the range of economic opportunities available to the property.

If the land were required to remain agricultural, its economic utilization would generally be constrained by the uses permitted under that classification. A tourism-development classification, by contrast, may open the property to alternative uses such as resorts, accommodation facilities, recreation, agritourism, restaurants, events, and related activities. The physical land may remain unchanged, but its opportunity set has expanded.

From an economic perspective, this expanded opportunity itself is significant because the property is no longer evaluated solely on the basis of its existing or historical agricultural use. Market participants may also consider the benefits that could reasonably be derived from the additional legally permissible uses.

Highest and Best Use Is Fundamentally Economic

This brings us to highest and best use, with its familiar four tests: physically possible, legally permissible, financially feasible, maximally productive. But underneath those tests is an economic question — among the alternative uses available to this scarce resource, which one is most productive given the applicable constraints and market conditions?

This is opportunity cost at work. A warehouse site can’t simultaneously be a residential subdivision. Agricultural land may have a tourism alternative. A residential lot on a commercial corner may have a more productive use waiting. The market evaluates not just what a property is, but what it can economically become — which is why highest and best use is one of the clearest intersections of appraisal and economics.

Utility, Scarcity, and Demand

Land is scarce, but scarcity alone doesn’t create value. An asset can be scarce and still worth relatively little if demand for its attributes is weak. Demand alone doesn’t explain value either, without considering the supply of substitutes. A highly accessible commercial corner in a growing area commands a premium because good alternatives are limited and demand is strong. A remote parcel is also physically unique — there’s only one property at its exact coordinates — but uniqueness alone doesn’t guarantee value if nobody wants what it offers.

Scarcity becomes economically meaningful only in relation to utility, demand, and available substitutes.

Buildings Should Be Understood Economically Too

The same logic applies to improvements. Two commercial buildings, each 10,000 square meters — identical by measurement. But one might have an efficient layout, good ceiling heights, modern systems, and strong tenant appeal, while the other has the same floor area with outdated systems and poor configuration. Equal physical quantity, unequal economic utility.

This is why depreciation isn’t just physical deterioration. Functional obsolescence is about diminished utility from the improvement’s own characteristics; external obsolescence comes from influences outside the property. A building can remain structurally sound while becoming economically less productive — which is also why physical life and economic life aren’t the same thing.

Cost Does Not Automatically Become Value

Suppose a developer spends ₱100 million on construction. That expenditure doesn’t guarantee the market will recognize ₱100 million of value. If the improvement meets market demand and generates real utility, the investment likely does contribute to value. But if it’s overbuilt, poorly designed, or wrong for its location, part of that cost may simply not be recognized by buyers.

The relevant question isn’t “how much was spent” — it’s “what economic utility did that spending actually create?” This matters directly in the Cost Approach: replacement or reproduction cost is only part of the analysis. The appraiser still has to determine how much of that cost continues to contribute economically to the property.

Time Is an Economic Component of Value

A development capable of producing ₱100 million today isn’t economically equivalent to one expected to produce the same amount ten years from now. Development takes time, infrastructure takes time, properties take time to sell, income properties take time to stabilize. Capital committed today has an opportunity cost; future benefits carry uncertainty.

So the real question isn’t “what benefits can this property eventually produce” — it’s “what are those future benefits worth today, given the cost, time, and uncertainty involved in realizing them?” That’s the economic foundation of present-value analysis, and one reason discounted cash flow techniques matter in the right assignments.

Risk Is Embedded in Value

Time and risk can’t be separated. Two properties might appear capable of producing similar future income but have very different values because the probability of actually realizing those benefits differs. One might have established tenants and predictable cash flow; another might depend on future approvals, major infrastructure spending, or years of market absorption. The expected benefits look similar — the risk profiles don’t. Market participants price that difference in, and so must the appraiser.

Expected Economic Benefits → adjusted for Costs, Time, and Risk → Present Economic Value

Risk isn’t an afterthought tacked onto the analysis — it’s one of the core mechanisms by which markets convert expectations about the future into present value.

Property Exists Within an Economic Environment

A new highway can improve accessibility. A port can stimulate industrial demand. A university can drive housing demand. Conversely, congestion, flooding, pollution, or declining economic activity can drag surrounding property down. In every case, the property itself hasn’t physically changed — its economic environment has. This is why inspecting the property alone can never fully explain its value; the appraiser also has to understand the economic system the property sits inside.

What This Means for the Professional Appraiser

Technical competence still matters — inspecting, measuring, understanding plans, construction, property rights, land-use controls. But professional competence also means thinking economically: What creates demand for this property? What limits its supply? What substitutes exist? What alternative uses compete for the site? What investment is needed to realize its opportunities? How long will that take, and what risk comes with it? How might infrastructure, regulation, population, or financing conditions change those expectations?

These aren’t questions separate from valuation. They’re questions about how value gets formed in the first place.

Conclusion: Property Is Physical; Value Is Economic

There’s nothing wrong with an appraiser proudly carrying a measuring wheel. The problem is confusing an understanding of a property’s physical dimensions with an understanding of its economic value.

A small access parcel can shape how a much larger property gets used. A zoning change can alter land’s economic possibilities without adding a single square meter to it. A road matters not for its measured width but for the economic connections it enables. A building can stay physically sound while losing economic relevance as markets and preferences shift. And vacant land with no improvements at all can embody substantial economic opportunity.

Property is physical. Value is economic.

We measure property to understand what exists. We study rights and institutions to understand what can be done with it. We analyze location and access to understand how it connects to economic activity. We study markets to understand demand and substitutes. And we apply economics to understand how utility, scarcity, opportunity, cost, time, and risk get converted into value.

The growth of an appraiser shouldn’t stop at getting better with a measuring wheel or laser measure. It should progress toward something harder, and more important: understanding the economics of the property being measured.

CASE NOTE #1-Easement of Right of Way

When the Valuation Premise Itself Must Be Tested

THE CHALLENGE

A property dispute involving an easement of right of way may initially appear to present a simple valuation question.

A proposed six-meter-wide right of way would affect approximately 655 square meters of a servient property while providing access to a 15,285-square-meter dominant estate. At first glance, the assignment appears straightforward: determine the value of the 655 square meters affected by the proposed easement.

But the area to be valued is itself based on assumptions that may materially affect the valuation result. Why this route? Why six meters? Would three or four meters adequately provide the required access? Are other feasible routes available? How would each alternative affect the servient and dominant estates?

The valuation problem therefore extends beyond assigning a unit value to the affected land. It requires determining the economic consequences of the proposed easement and its feasible alternatives.

THE AA+ CONSULTING APPROACH

AA+ does not begin by simply multiplying 655 square meters by a unit value. We first examine whether the assumptions defining the valuation problem should themselves be tested.

Alternative routes and widths are identified and evaluated as separate property scenarios. For each feasible configuration, the analysis considers the area burdened, the resulting effect on the use and development potential of the servient estate, and any corresponding diminution in its market value.

The analysis also examines the other side of the transaction. Access created over a relatively small portion of one property may materially affect the utility, development potential, highest and best use, marketability, and value of a much larger dominant estate. The economic effect of access must therefore be distinguished from the value of the land physically occupied by the easement.

AA+ does not determine which route or width the law ultimately requires. That determination belongs to the appropriate legal decision-maker. Our role is to transform the property and economic issues embedded in the dispute into independently supportable valuation evidence.

In Litigation Valuation & Consulting,  sometimes the difficult valuation question is not “What is the value?” but “What exactly should be valued, and why?”

Consulting identifies the valuation problem. Valuation measures its economic consequences. Expert evidence brings that analysis into the adjudicative process.

AA+ APPRAISAL & CONSULTANCY, INC.
Litigation Valuation & Consulting
When Property Value Becomes the Dispute

Article 4 and the Fight Over Wage Order NCR-27

The controversy surrounding NCR Wage Order No. 27 is not simply a dispute over an ₱85 minimum-wage increase. At its core is a more fundamental question about the allocation of governmental authority: when Congress creates a specialized mechanism for fixing and reviewing minimum wages, may an employer sidestep that mechanism, seek declaratory relief from a Regional Trial Court, and obtain an injunction against a wage order’s implementation?

That question is now before the Supreme Court, on a Petition for Certiorari and Prohibition filed by labor organizations challenging RTC orders that restrained the implementation of Wage Order No. NCR-27. The petition asks, among other things, whether RTCs may issue TROs or injunctions against wage orders despite Article 126 of the Labor Code, whether declaratory relief is available despite the specific administrative remedy under Article 123, and whether the RTCs committed grave abuse of discretion in entertaining the cases at all.

The dispute sits at the intersection of labor law, administrative law, remedial law, and statutory construction. But one provision deserves more attention than it has so far received: Article 4 of the Labor Code. Interestingly, the pending petition does not expressly develop Article 4 as part of its statutory-construction argument — an omission that opens an important additional line of analysis.

Congress Built a Specialized Wage-Setting System

The starting point is Republic Act No. 6727, the Wage Rationalization Act of 1989. It created the Regional Tripartite Wages and Productivity Boards (RTWPBs) to determine and fix regional minimum wages, with the National Wages and Productivity Commission (NWPC) exercising supervisory and review functions over them.

This was a deliberate institutional choice. Minimum-wage determination requires weighing the cost of living, workers’ needs, prevailing wage levels, employers’ capacity to pay, employment generation, and reasonable returns on investment — not questions of law alone, but ones demanding economic data, policy judgment, consultation, and specialized expertise. The Supreme Court has accordingly characterized the issuance of a wage order as an exercise of quasi-legislative power delegated by Congress, and the pending petition itself invokes Metropolitan Bank and Trust Co. v. NWPC for that proposition.

The statutory division of labor can be summarized simply:

  • RTWPB — fixes regional minimum wages
  • NWPC — administratively reviews wage orders
  • Courts — exercise judicial review, when properly invoked

NCR-27 tests the boundaries between these three functions.

From the RTWPB to the RTC

According to the petition, RTWPB-NCR issued Wage Order No. NCR-27 on June 23, 2026, providing for a phased increase of ₱60 effective July 25, 2026 and a further ₱25 effective January 20, 2027 — a total adjustment of ₱85.

On July 23, Readycon Trading and Construction Corporation and R-II Builders, Inc. filed a Petition for Declaratory Relief with Prayer for Preliminary Injunction, TRO and/or Status Quo Ante Order before the Pasig RTC. The court subsequently issued orders restraining implementation of the wage increase. A separate Rule 63 petition involving NCR-27 was also filed before the Navotas RTC.

This raises an obvious procedural question: why resort to declaratory relief when the Labor Code already provides a remedy for a party aggrieved by a wage order?

Article 123 Already Tells an Aggrieved Employer What to Do

Article 123 supplies a specific administrative remedy. An aggrieved party may appeal a wage order to the NWPC within ten calendar days of publication, and the NWPC must decide that appeal within sixty calendar days.

Crucially, Congress also decided what happens to the wage order while the appeal is pending: filing an appeal does not stay the order, unless the appellant posts an undertaking, with satisfactory sureties, to pay the wage increase should the order be affirmed.

In other words, Congress didn’t just name an appellate body — it specified who may challenge a wage order, when, where, how quickly the challenge must be resolved, and whether the challenge suspends implementation in the meantime.

The statutory route looks like this:

RTWPB → Wage Order → NWPC Appeal (no automatic stay)

What happened in the challenged cases looks like this instead:

RTWPB → Wage Order → RTC Declaratory Relief → TRO/Injunction (wage increase stopped)

That distinction is precisely why the pending petition argues that Rule 63 is being used as a substitute for a lost Article 123 appeal — one of the central questions petitioners want the Supreme Court to resolve.

But What Exactly Is There to “Declare”?

There’s a more basic question underneath the procedural one. Declaratory relief exists to resolve genuine uncertainty about legal rights and obligations before any breach occurs — it is preventive, not corrective. But disagreement with a governmental decision is not the same thing as ambiguity in the governing law.

Article 123 already tells an aggrieved employer exactly what remedy to pursue. Article 126 separately restricts judicial injunctions against proceedings before the NWPC and the Regional Boards. The statutory wage-setting mechanism has existed since 1989 — yet the pending petition itself describes the use of declaratory relief against wage orders as a novel maneuver deserving definitive Supreme Court guidance.

That produces a logically prior question: if the Labor Code already tells an aggrieved employer where to go, when to appeal, what happens during the appeal, and what courts may not enjoin, what exactly is left for an RTC to “declare”?

A party’s dissatisfaction with the legal consequences of a statute does not, by itself, create the kind of uncertainty Rule 63 contemplates. None of this means wage orders are immune from judicial review — they plainly are not. The real issue is whether declaratory relief is the proper vehicle, especially where Congress has already supplied a special statutory remedy.

A Lost Appeal Cannot Simply Become Declaratory Relief

The petition makes this argument directly: the employers failed to exhaust the administrative remedy under Article 123, and declaratory relief cannot serve as a substitute for a lost appeal.

Consider the alternative. Congress gives an aggrieved employer ten days to appeal a wage order. The employer lets that period lapse. It then files a declaratory-relief petition challenging the same wage order and obtains an injunction anyway. If that route is freely available, what remains of the ten-day statutory appeal period? The issue, then, is not merely procedural preference — it’s whether a general remedy under Rule 63 may be used to circumvent a special remedy that the Labor Code specifically created.

Primary Jurisdiction: Courts Are Not Wage Boards

The controversy also implicates the doctrine of primary jurisdiction — the principle that courts ordinarily defer, in the first instance, to questions Congress has placed within an administrative agency’s special competence, particularly where specialized expertise is required.

This matters most where an employer’s objections concern:

  • capacity to pay
  • reasonable returns on investment
  • economic impact
  • employment consequences
  • the proper amount of the wage adjustment

These are exactly the kinds of economic questions the RTWPBs were created to evaluate. The distinction that matters is between judicial review — asking whether the RTWPB acted according to law — and judicial substitution — a court reweighing the economic considerations Congress entrusted to the RTWPB in the first place. Courts retain the power to determine legality and constitutionality, but that doesn’t make an RTC an alternative wage-setting or appellate body.

Article 126 and the Anti-Injunction Question

Article 126 provides that “no preliminary or permanent injunction or temporary restraining order may be issued by any court, tribunal or other entity against any proceedings before the Commission or the Regional Boards.”

Petitioners argue this prohibition bars courts from restraining NCR-27, and that a status quo ante order cannot accomplish indirectly what the law forbids directly. But the text raises an interesting wrinkle: Article 126 refers to “proceedings before the Commission or the Regional Boards” — it does not expressly say “implementation of an already-issued wage order.”

An employer could therefore advance a narrow textual reading: once the RTWPB completes its hearings and issues the wage order, the “proceedings before” the Board have ended, so an injunction against subsequent implementation is not literally an injunction against an ongoing proceeding. That is arguably the strongest textual counterargument available to the employers.

But Article 126 does not exist in isolation.

Articles 123 and 126 Must Be Read as One Statutory Scheme

Article 123 establishes the means for challenging a wage order and deliberately provides that an appeal does not automatically stay it. Article 126 restricts judicial injunctions against proceedings before the wage-setting authorities. Read together, they reveal a coherent design:

RTWPB → Wage Order → NWPC review → no automatic suspension of the wage order

Compare that to the RTC route actually taken:

RTWPB → Wage Order → Rule 63 declaratory relief → TRO/Injunction → wage order suspended

A general judicial remedy would then accomplish exactly what the special statutory remedy was designed not to automatically allow. The petition argues that Congress structured Article 123 to protect workers from losing a wage increase during the review process, and that a judicial stay obtained outside that mechanism defeats the design. This is where statutory construction — and Article 4 — becomes central.

The Missing Interpretive Rule: Article 4 of the Labor Code

The pending petition develops Articles 123 and 126 extensively, along with declaratory relief, exhaustion of administrative remedies, primary jurisdiction, and the constitutional mandate to protect labor. What it does not expressly develop is Article 4 as an independent rule of statutory construction.

Article 4 provides that all doubts in the implementation and interpretation of the Labor Code and its implementing rules shall be resolved in favor of labor. How much weight this provision deserves depends entirely on how the Court reads Article 126.

If Article 126 is clear, apply it as written. Petitioners’ primary position is that Article 126 is unambiguous. If that’s correct, Article 4 has no work to do — a clear statute is applied, not construed. But that conclusion cuts both ways: if Article 126 is already clear, where is the uncertainty that supposedly justified declaratory relief in the first place? Article 123 is equally clear about the administrative remedy available to an aggrieved employer. If both provisions are unambiguous, the threshold question isn’t how an RTC should interpret them — it’s why declaratory relief was necessary at all. Disagreement with a wage order is not the same as uncertainty about what the law means.

If Article 126 is ambiguous, Article 4 arguably enters the analysis. Suppose the Court were to accept that the phrase “proceedings before the Commission or the Regional Boards” creates genuine uncertainty as applied to an injunction against an already-issued wage order’s implementation. Under ordinary canons of statutory construction, the analysis would then typically proceed in stages: first, harmonizing Articles 123 and 126 as one statutory scheme rather than reading either in isolation; and only if genuine doubt survived that harmonization, turning to Article 4, which directs that residual doubt be resolved in favor of labor. On this view, Article 4 functions not as a rhetorical appeal to social justice but as a legislatively prescribed interpretive rule — part of the very statute whose meaning is in dispute.

The Declaratory-Relief Dilemma

This produces what may be the sharpest tension in the whole controversy:

  • If there is no ambiguity, why is declaratory relief necessary?
  • If there is genuine ambiguity, what role is left for Article 4 to play in resolving it?

Article 4 cannot manufacture ambiguity, cure jurisdictional defects, or eliminate an employer’s legal rights — it doesn’t decide the case by itself. But it creates a real interpretive bind: the harder a party argues that the law is uncertain to justify going to the RTC, the more relevant the Labor Code’s own rule for resolving that uncertainty becomes. And the harder a party insists the law is already clear, the harder it becomes to explain what declaratory relief was supposed to declare in the first place.

A Three-Level Framework, If One Were to Build It

One way petitioners could structure this argument, drawing on ordinary canons of construction, is in three levels, applied in sequence:

  1. Plain meaning. If Articles 123 and 126 are clear, apply them as written. Article 123 supplies the specific remedy; Article 126 supplies the restriction on injunctive intervention.
  2. Harmonization. If Article 126 requires interpretation, read it alongside Article 123 so that a general Rule 63 remedy doesn’t defeat the special review mechanism Congress deliberately built.
  3. Article 4. If genuine doubt survives even after harmonization, Article 4 directs that it be resolved in favor of labor.

That kind of sequence would be considerably stronger, as a matter of legal method, than simply invoking “labor should always be favored” — it starts from text, moves to the statutory scheme as a whole, and reaches Article 4 only as a last resort. Whether the Court adopts this or any other framework is, of course, for the Court to decide.

Rule 63 Has Another Problem: Necessary Parties

Even setting aside whether declaratory relief was theoretically available, the petition raises a separate procedural defect: Rule 63 requires that persons who have or claim an interest affected by the declaration be made parties to the case. According to the petition, the labor organizations that initiated the wage petitions leading to NCR-27 were never impleaded in the RTC proceedings.

Taken together, the Rule 63 controversy involves several distinct, connected questions:

  • Was there genuine uncertainty appropriate for declaratory relief?
  • Can Rule 63 bypass Article 123’s special remedy?
  • Can declaratory relief substitute for a lost appeal?
  • Does primary jurisdiction require resort to the specialized administrative mechanism first?
  • Were all interested parties joined?
  • Can the RTC issue injunctive relief at all, given Article 126?

Why Certiorari and Prohibition?

The labor organizations went to the Supreme Court through Rule 65, not to argue that ₱85 is the economically correct figure, but to challenge the RTCs’ authority to entertain the Rule 63 cases and issue restraining orders — alleging grave abuse of discretion amounting to lack or excess of jurisdiction. Certiorari seeks to annul judicial acts already performed with grave abuse of discretion; prohibition seeks to stop courts from continuing proceedings allegedly beyond their lawful authority. Because the petition was filed directly with the Supreme Court, petitioners also invoke recognized exceptions to the hierarchy of courts: transcendental importance, a case of first impression, pure questions of law, public welfare, patent nullity, and the absence of any other plain, speedy, and adequate remedy.

What If the Immediate Controversy Becomes Moot?

TROs expire. Injunctions may be lifted. Wage orders may eventually take effect. The petition anticipates this and argues that the Court has discretion to resolve the legal questions anyway, citing the public interest at stake, the need for guidance to the Bench and Bar, and the likelihood that this same pattern will recur:

RTWPB issues a wage order → employer files declaratory relief → RTC issues a TRO or injunction → implementation is delayed → the immediate controversy eventually disappears → another wage order produces another case

Without definitive guidance, this cycle could repeat indefinitely — which is why the eventual ruling may shape the procedure for challenging every future wage order, not just NCR-27.

Does Judicial Intervention Render the RTWPB Inutile?

Courts retain constitutional judicial power, and no administrative agency can insulate itself from judicial review simply by claiming specialized expertise. But that isn’t really the question here. The better question is: at what point does judicial review become judicial substitution?

If every wage order can routinely travel from RTWPB, to wage order, to RTC declaratory relief, to injunction, to prolonged litigation, the specialized administrative system Congress built risks being hollowed out in practice. The institutional line Congress drew is that RTWPB and NWPC handle wage policy and specialized economic determinations, while courts police legality and constitutionality. Judicial review is meant to keep administrative agencies within the law, not to function as a substitute RTWPB or NWPC — a distinction the Court will ultimately have to draw for itself in this case.

The Question That Deserves an Answer

The NCR-27 controversy is ultimately about more than an ₱85 wage increase. It asks whether a general procedural remedy under Rule 63 can be used to bypass a special statutory mechanism that has governed regional wage-setting since R.A. No. 6727 was enacted in 1989.

The pending petition builds a substantial case around Articles 123 and 126, primary jurisdiction, exhaustion of administrative remedies, Rule 63, and the constitutional protection of labor. Article 4 adds one more dimension worth taking seriously. Stated as a general interpretive framework: a clear law is applied as written; a specific remedy like Article 123 is meant to be used, not revived through a different procedural door once its window has closed; an ambiguous provision like Article 126 is read together with the rest of the statutory scheme; and only if genuine doubt survives that exercise does Article 4 direct that it be resolved in favor of labor. Whether that framework — or some other — governs NCR-27 is squarely the Court’s call to make.

Which leaves the question the Court will ultimately have to answer: if Articles 123 and 126 are clear, what was there for the RTC to declare? And if they are genuinely ambiguous, what happens to that ambiguity under Article 4?

The Supreme Court has not yet spoken. Until it does, the arguments in the pending petition remain just that — arguments, not controlling doctrine. But the case gives the Court a real opportunity to define the relationship between declaratory relief and special statutory remedies, between judicial review and administrative expertise, and between judicial intervention and the wage-setting authority Congress deliberately entrusted to the RTWPBs and the NWPC.


This article is offered for informational and educational discussion of a matter of public interest, and does not constitute legal advice or an attempt to influence the outcome of any pending case. The characterization of facts and arguments reflects the contents of the petition as filed; the interpretive frameworks discussed are analytical possibilities, not predictions or recommendations as to how the Supreme Court should rule. Readers should consult the actual pleadings and any subsequent Court rulings for authoritative guidance.

RESA Month Reflection: Economics as the Foundation of Philippine Real Estate Practice

Every August, the Philippine real estate profession celebrates the enactment of the Real Estate Service Act (RESA), a landmark law that professionalized real estate brokerage, appraisal, and consultancy.

The significance of RESA extends beyond licensure. Its Declaration of Policy recognizes that the real estate service profession plays a vital role in national development by promoting the growth of the real estate industry, protecting the public interest, and ensuring that the services rendered by real estate professionals contribute to economic progress through competent, ethical, and globally competitive practice.

Continue reading “RESA Month Reflection: Economics as the Foundation of Philippine Real Estate Practice”

From MEPZ III to SM Arena: What the South Road Properties Tell Us About the Philippine Economy

Yesterday, while driving home from southern Cebu, I found myself caught in an unusually heavy traffic buildup along the South Road Properties (SRP). At first, I wondered what was causing the congestion. Moments later, I realized that people were making their way to the grand opening of SM Arena Seaside Cebu.

The Arena is an impressive addition to Cebu’s urban landscape—a 19,000–square-meter indoor events venue with a seating capacity of up to 25,000, placing it among the largest event venues in the country. Its opening symbolizes how investment priorities in SRP have shifted over the past three decades—from an industrial growth strategy toward one centered on commerce, tourism, entertainment, institutional uses, and other service-oriented activities.

Continue reading “From MEPZ III to SM Arena: What the South Road Properties Tell Us About the Philippine Economy”

Beyond the Hotel: Complex Hospitality Valuation in Rehabilitation Proceedings

Open hotel appraisal report showing property overview and financial metrics

One of the privileges of professional practice is the opportunity to work on assignments that challenge not only technical competence but also one’s understanding of economics, law, and property rights.

Our team had the opportunity to undertake two major hospitality valuation assignments in support of corporate rehabilitation proceedings. While confidentiality prevents disclosure of the parties, the engagements involved substantial hospitality assets in Zambales and Tagaytay. They required the application of appraisal principles beyond conventional real estate valuation.

One assignment involved a hospitality development consisting of two five-storey hotel buildings, together with a clubhouse, basement parking, swimming pool, landscaped amenities, function facilities, and more than one hundred individually titled accommodation and commercial units. The complexity of the property required careful analysis of both the physical assets and the legal interests represented by numerous condominium titles.

The second assignment involved another large-scale hospitality village developed on approximately four hectares of land. The property consisted of three multi-storey villa buildings with a combined gross floor area approaching 16,000 square meters, complemented by recreational facilities including a clubhouse, swimming pool, tennis court, landscaped parking areas, and other resort amenities. Unlike the first assignment, however, the underlying land was held under a long-term government lease, requiring the valuation to distinguish between the leasehold interest over the land and the ownership of the buildings and improvements.

These engagements reinforced an important realization.

In complex litigation and rehabilitation proceedings, valuation is no longer about estimating what a property could sell for. It is about understanding what legal rights exist, what economic opportunities those rights create, and how those rights influence value.

Two hotels may appear similar in terms of buildings, rooms, and operations. Yet they may have materially different market values because the underlying property rights differ.

This is precisely why our consulting practice has continued to develop what we refer to as the Evidence-Based Valuation Framework.

Rather than beginning solely with comparable sales, the framework first identifies the property rights involved before systematically examining physical, legal, planning, economic, and market evidence. The final opinion of value is therefore not simply an estimate—it is the conclusion supported by a comprehensive body of evidence.

Assignments such as these demonstrate the expanding role of modern valuation practice. Today’s appraiser is expected not only to measure value but also to explain the legal and economic foundations upon which that value rests. This is particularly important in rehabilitation proceedings, where valuation evidence assists the court, creditors, rehabilitation receivers, and other stakeholders in making informed decisions regarding financially distressed assets.

For us, every engagement is an opportunity to demonstrate that valuation is more than determining a number.

It is the disciplined application of economics, property law, planning, and market evidence to arrive at an opinion that is credible, transparent, and capable of withstanding professional and judicial scrutiny.

The future of valuation lies not merely in producing credible numbers, but in presenting credible evidence.

Ten Questions to Ask Before Accepting an Expropriation Assignment

By Augusto B. Agosto, REA, REC, REB, EnP, JD

This morning, a newly licensed appraiser asked me a question:

“How do I start an expropriation appraisal assignment?”

Many appraisers immediately think about comparable sales, market data, or valuation methodology. While these are important, I believe the first steps occur long before the valuation process begins.

Expropriation is not a simple and ordinary appraisal assignment. It is a judicial proceeding involving property rights, public interest, legal procedures, and the constitutional requirement of just compensation. An appraiser appointed by the court, whether as Commissioner or member of a Board of Commissioners, carries a responsibility that extends beyond determining market value.

Over the years, I have developed a series of questions that I ask myself before accepting an expropriation assignment.

1. Am I a Disinterested Person?

The first document I request from the client is a copy of the Complaint.

Before discussing value, I want to know:

  • Who are the parties?
  • What property is involved?
  • What is the nature of the taking?
  • Do I have any relationship with the parties?

This allows me to determine whether there is any actual or perceived conflict of interest.

The Rules of Court require a Commissioner to be a disinterested and competent person. Independence is therefore not merely an ethical consideration—it is a legal requirement.

2. Am I Competent to Accept This Assignment?

The next question is equally important.

Do I possess the competence required by the Court for this particular case?

Expropriation requires more than valuation knowledge. An appraiser must understand the legal framework governing the proceeding.

Among the important laws and rules that should be familiar to an expropriation appraiser are:

  • Rule 67 of the Rules of Court (Expropriation)
  • Rule 32 of the Rules of Court (Commissioners)
  • RA No. 8974 and its amendments
  • RA No. 12001 RPVARA
  • The ARROW Act and its Implementing Rules
  • Comprehensive Agrarian Reform Law
  • Local Government Code
  • Relevant jurisprudence on just compensation and property rights

Understanding these laws allows the appraiser to appreciate the broader litigation process, the role of the parties, the duties of the commissioners, and the standards by which the court evaluates evidence.

3. Who Is the Expropriating Authority?

Another important question is:

Who is exercising the power of eminent domain?

Is it:

  • A national government agency?
  • A government-owned or controlled corporation?
  • A local government unit?
  • A utility company exercising delegated eminent domain powers?
  • Another entity authorized by law?

The answer helps determine the applicable legal framework, the procedures involved, the source of funding, and the nature of the project.

For example, national government infrastructure projects may involve RA No. 8974, RA No. 12001, the ARROW Act, and related regulations. Local government expropriations may involve different statutory requirements under the Local Government Code. Utility companies and government corporations may likewise operate under special laws.

Before determining value, the appraiser must first understand who is taking the property and under what authority such taking is being exercised.

4. What Property Right Is Being Taken?

One of the most common mistakes is assuming that every expropriation involves the acquisition of full ownership.

Not all takings are the same.

The government may acquire:

  • Fee simple ownership
  • Right-of-way
  • Easement
  • Transmission line corridor
  • Temporary construction easement
  • Access rights
  • Portions of improvements

Before value can be determined, the property right being acquired must first be identified.

You cannot value what you have not properly defined.

5. What is the Time of Taking?

One of the most important questions in any expropriation assignment is:

What is the legally recognized date of taking?

Many appraisers mistakenly assume that valuation is always based on the current value of the property or that the date of taking is uniform across all compulsory acquisitions. In reality, the applicable valuation date often depends on the governing law, the nature of the acquisition, and the circumstances of the case.

For example, infrastructure right-of-way acquisitions, traditional expropriation proceedings under Rule 67, and agrarian reform acquisitions may involve different legal frameworks and different approaches in determining the relevant date for valuation.

In agrarian reform cases, the issuance of a Notice of Coverage does not automatically constitute the date of taking. While it marks the commencement of the acquisition process, jurisprudence has recognized that the determination of the date of taking requires an examination of when the landowner was effectively deprived of ownership rights, possession, use, enjoyment, or economic benefits of the property, as contemplated by the governing agrarian laws.

Similarly, in infrastructure and right-of-way acquisitions, the legally relevant date may be influenced by statutory provisions governing possession, entry, deposits, negotiated acquisition, and expropriation proceedings.

The valuation date is not merely a procedural matter. It is often one of the most significant legal issues in the determination of just compensation. A difference of several years between the date of taking and the date of appraisal can substantially affect the value conclusion and the amount ultimately awarded by the court.

Before determining value, the appraiser must first determine the applicable law, identify the legally relevant date of taking, and understand the jurisprudence governing that acquisition.

The question is not:

“What is the property worth today?”

The more important question is:

“What was the property worth on the date recognized by law for purposes of determining just compensation?”

6. What Standard of Value Is Required?

Many appraisers immediately think in terms of market value.

However, the court is often concerned with just compensation.

The two concepts are related but not always identical.

An appraiser must understand:

  • Market value
  • Just compensation
  • Consequential damages
  • Consequential benefits
  • Compensation for improvements
  • Compensation for crops and other affected interests

Understanding the applicable legal standard is essential.

7. What Evidence Supports My Opinion?

The first question should not be:

“What comparables are available?”

The better question is:

“What evidence is available?”

Comparable sales are important, but they are only one form of evidence.

The appraiser must also examine:

  • Property characteristics
  • Property rights
  • Legal conditions
  • Planning evidence
  • Economic evidence
  • Market evidence

A valuation that relies solely on comparable sales may fail to capture the broader realities affecting value.

8. How will I personally inspect the Property?

No amount of documentation can replace actual inspection.

Titles, plans, and tax declarations provide information.

Site inspection provides understanding.

Actual inspection often reveals:

  • Existing access
  • Physical conditions
  • Occupation
  • Improvements
  • Constraints
  • Opportunities

Many critical valuation issues are discovered only in the field.

9. Can the Judge Understand My Report?

One of the purposes of a Commissioner’s Report is to assist the court.

A technically correct report that cannot be understood by the judge has failed in one of its essential functions.

The appraiser must be able to explain:

  • The facts
  • The evidence
  • The reasoning
  • The conclusions

in a clear and understandable manner.

10. Can I Defend My Opinion Under Oath?

Every valuation submitted to the court will be examined, questioned, and challenged.

Ask yourself:

  • Are my comparables defensible?
  • Are my adjustments supported?
  • Is the highest and best use justified?
  • Have I verified the title?
  • Have I disclosed limitations and assumptions?

A report should be prepared with the expectation that it will be scrutinized by lawyers, judges, and other experts.

Before submitting any report, I ask myself one final question: If I am placed on the witness stand tomorrow, can I confidently explain every assumption, adjustment, conclusion, and recommendation contained in this report?

If the answer is no, more work is required.

The report is not yet ready.

Conclusion

Expropriation appraisal is not merely an exercise in determining value.

It is the process of assisting the court in determining just compensation for the taking of private property.

The appraiser’s role therefore extends beyond market analysis. It requires competence in property rights, valuation, evidence, legal procedure, and professional judgment.

In my experience, the most important question is not:

“Can I determine value?”

The more important question is:

“Can my valuation withstand the scrutiny of the court?”

That is where expropriation appraisal truly begins.

When an Easement Right-of-Way Creates Millions in Value: The Hidden Power of Property Rights

Most people think property value comes from land area, location, or improvements. While these factors are important, one of the most overlooked drivers of value is the existence—or absence—of property rights.

A recent property rights assignment involving an interior urban property illustrates this principle.

The assignment initially appeared straightforward. The property itself was an interior parcel located within an established urban area. At first glance, the issue seemed to involve only a narrow access corridor used for ingress and egress. The physical area involved was relatively small compared to the overall property.

Yet as the investigation progressed, it became apparent that the dispute was not really about land.

It was about rights.

For many years, neighboring property owners had relied on a shared access arrangement that allowed vehicles and pedestrians to reach the interior property. The arrangement had existed for so long that it became part of the ordinary use of the area. Access was rarely questioned because it was always available.

Over time, however, questions emerged regarding the legal basis of the access. Could the arrangement continue? Was the right enforceable? Could it be withdrawn? If access were restricted, what would happen to the value and utility of the property behind it?

At first glance, these appear to be legal questions.

In reality, they are also valuation questions.

Because the moment access becomes uncertain, the economic character of a property changes.

A parcel of land may remain in the same location. Its boundaries may remain unchanged. Its area may remain exactly the same. Yet the usefulness, marketability, financing potential, and development opportunities associated with that property may increase or decrease dramatically depending on the rights attached to it.

This is a reality often overlooked in conventional real estate analysis.

Many valuation discussions focus on square meters, comparable sales, and market trends. These are important considerations. However, some of the most valuable attributes of a property are not visible on the ground. They exist in the form of property rights.

A right-of-way.

An easement.

A development permit.

A zoning entitlement.

A water right.

A development restriction.

Each of these rights can significantly influence value without changing the physical characteristics of the property.

As our analysis progressed, it became evident that the access corridor was doing something extraordinary.

It was unlocking the economic potential of an entire property.

Without secure access, the property’s utility would be substantially impaired. Marketability would decline. Financing options could become limited. Development opportunities would be constrained.

With access, however, the property could fully participate in the market.

The difference in value was measured not merely in terms of land area, but in terms of economic opportunity.

The assignment reinforced a lesson that I have repeatedly encountered throughout my professional career.

Whether dealing with easements, expropriation, water rights, development restrictions, estate settlements, or land use planning, the most important issue is often not the land itself.

The real issue is the bundle of rights attached to the land.

Who owns those rights?

Who may exercise them?

Who benefits from them?

Who bears the burden?

And ultimately, who captures the value they create?

These questions are becoming increasingly important as infrastructure projects, urban development, environmental regulations, and land use policies continue to reshape the economic landscape.

At AA+ Appraisal & Consultancy, Inc., we believe that before value can be measured, rights must first be understood.

This is why our work extends beyond traditional appraisal.

We examine ownership rights, access rights, development rights, planning constraints, legal restrictions, and economic opportunities. We seek to understand not only what a property is worth, but why it is worth that amount.

Because in many cases, the most valuable part of a property is not the land.

It is the rights attached to it.

And when those rights are properly understood, protected, and analyzed, hidden value often becomes visible.

That is where meaningful property advice begins.


Value is created by rights, not merely by land.

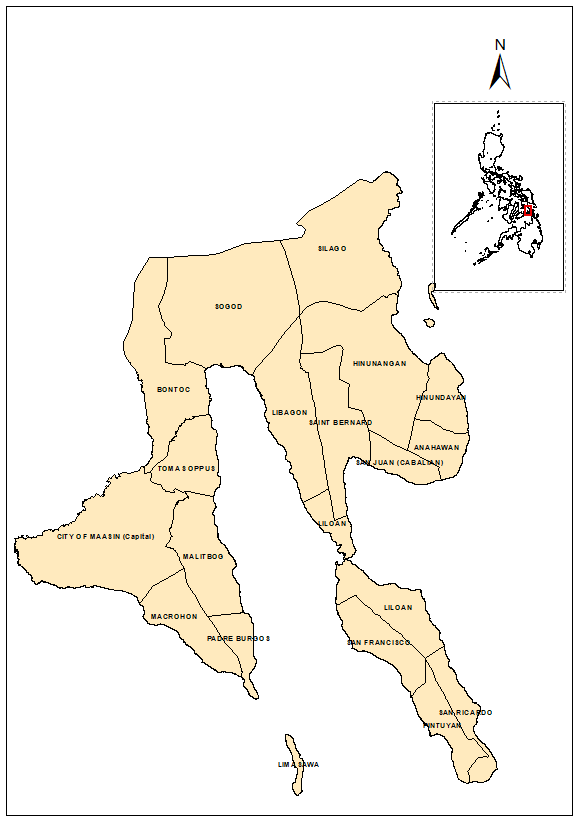
Southern Leyte: A Province Between the Sea, the Mountains, and Opportunity

When investors discuss opportunities in Eastern Visayas, attention often gravitates toward Tacloban City, Leyte, and Samar. Yet beyond the region’s established centers lies a province quietly positioning itself for future growth—Southern Leyte.

Traditionally viewed as an agricultural province, Southern Leyte is increasingly emerging as a strategic growth corridor driven by transportation connectivity, tourism development, public infrastructure investments, and its unique position as the gateway between the Visayas and Mindanao.

While it may not yet command the same level of investment attention as larger provinces, many of the ingredients necessary for long-term economic expansion are already in place.

Strategic Location: The Province’s Strongest Asset

Geography often determines economic destiny.

Southern Leyte occupies a critical location at the southern end of Leyte Island, serving as the principal land and sea connection between Eastern Visayas and Northeastern Mindanao. The Liloan–Surigao route is one of the busiest inter-island transport links in the country, facilitating the movement of passengers, agricultural products, consumer goods, and commercial cargo.

This strategic position provides Southern Leyte with a natural competitive advantage in logistics, transportation, warehousing, and trade-related activities. As national infrastructure programs continue to improve roads, ports, and digital connectivity, the province stands to benefit from increased regional integration and economic mobility.

A Multi-Centered Provincial Economy

Unlike provinces dominated by a single urban center, Southern Leyte is developing through multiple growth nodes.

As the provincial capital, Maasin City functions as the center of government, education, healthcare, finance, and commerce. It serves as the primary urban market for the province and remains the focal point for public and private investments.

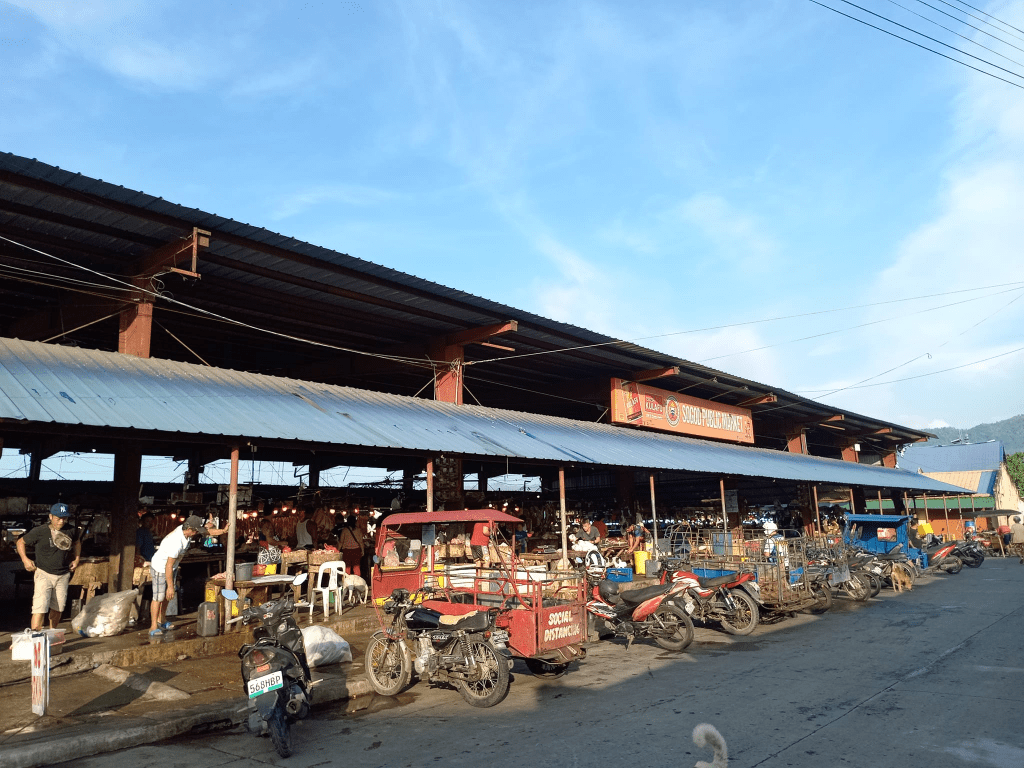
Sogod, the province’s only first-class municipality, has become an important commercial and transportation hub. Located along the Sogod Bay area, it serves as a crossroads connecting various municipalities and facilitating regional trade.

Hinunangan and neighboring municipalities provide agricultural production, fisheries resources, and growing commercial activity that contribute significantly to the provincial economy.

Together, these centers create a more resilient economic structure by distributing opportunities across the province rather than concentrating development in a single location.

Competitive Advantage and Economic Driver

While agriculture is often viewed as a traditional sector, it continues to provide Southern Leyte with a strong economic foundation.

The province’s major products include:

  • Coconut
  • Rice
  • Abaca
  • Fisheries products
  • Fruits and vegetables

Among these, abaca deserves special attention. As global industries increasingly seek sustainable and natural fibers, abaca presents opportunities for value-added processing, manufacturing, and export-oriented enterprises.

The challenge moving forward is not simply increasing production but strengthening agricultural value chains through processing facilities, logistics systems, market access, and technology adoption.

Southern Leyte possesses one of the most underappreciated tourism portfolios in the country.

Its attractions include:

  • Sogod Bay’s marine ecosystems
  • Whale shark encounters
  • Diving destinations
  • Limasawa Island, recognized as the site of the first recorded Easter Mass in the Philippines
  • Waterfalls, caves, and mountain landscapes
  • Coastal ecotourism destinations

Unlike highly urbanized tourism centers that face congestion and environmental pressures, Southern Leyte still enjoys the advantage of relatively intact natural resources.

This creates opportunities for sustainable tourism investments, including:

  • Eco-resorts
  • Dive tourism facilities
  • Adventure tourism
  • Community-based tourism enterprises
  • Heritage tourism development

As global tourism trends increasingly favor authentic and environmentally responsible experiences, Southern Leyte is well-positioned to compete.

Compared with highly urbanized markets, land values in many parts of Southern Leyte remain relatively affordable, creating opportunities for long-term investors willing to take a strategic view of future growth.

The province’s demographic expansion, infrastructure improvements, and economic diversification suggest that urban land demand is likely to increase over time.

Infrastructure as a Growth Catalyst

Infrastructure development continues to transform the province’s economic landscape.

Key assets include:

  • Pan-Philippine Highway connectivity
  • Maasin Port
  • Liloan Port
  • Roll-on/Roll-off ferry facilities
  • Expanding telecommunications infrastructure
  • Ongoing road improvement projects

These investments reduce transportation costs, improve market accessibility, and increase the attractiveness of the province for private investment.

Infrastructure not only supports economic activity—it also shapes future land values and development patterns.

Southern Leyte may not yet be considered a major investment destination, but many indicators suggest that its trajectory is changing.

Its strategic location, agricultural strengths, tourism assets, growing infrastructure network, and relatively affordable land base provide a foundation for long-term economic development.

My trip to Sogod, Southern Leyte.

The Cebu City Real Property Tax Shock: Why Market Modernization Must Not Kill the “Actual Use” Doctrine

Cebu City has undergone an undeniable spatial and economic transformation over the past two decades. From the gleaming corporate towers of Cebu Business Park and IT Park to the booming residential subdivisions in Guadalupe and the expanding luxury hillsides of Busay, our metropolitan footprint has expanded at a breathtaking pace.

But behind this economic success story lies a frozen fiscal reality: our local tax assessment schedules haven’t been updated since 2003.

Now, under the mandatory directive of Republic Act No. 12001, otherwise known as the Real Property Valuation and Assessment Reform Act (RPVARA), Cebu City is preparing to unleash one of the most sweeping real property tax recalibrations in its contemporary history.

As an appraiser, environmental planner, and economist, I know firsthand that updating these ancient schedules is a statutory necessity to wipe out passive land speculation. But the sheer velocity and underlying philosophy of Cebu City’s proposed Schedule of Market Values (SMV) and Schedule of Base Unit Construction Cost (SBUCC) should make every property owner stop and look at the fine print.

Here is why the current draft framework is setting up an explosive collision between aggressive market-driven valuation and your statutory rights as a taxpayer.

1. The Core Legal Battle: Market Appraisal vs. “Actual Use” Taxation

The ultimate friction point in the city’s new plan is a fundamental misinterpretation of how RPVARA interacts with the long-standing “Actual Use” Doctrine codified under Section 217 of the Local Government Code of 1991.

The law states with absolute clarity:

“Real property shall be classified, valued and assessed on the basis of its actual use regardless of where located, whoever owns it, and whoever uses it.”

For decades, this rule has protected long-time citizens from being taxed out of their own neighborhoods. It dictates that you must be taxed on how you are currently using your land, not on what your land could be worth if you knocked it down and built a commercial shopping mall.

While RPVARA introduces international appraisal standards to calculate true, prevailing market values, it did not repeal Section 217 of the Local Government Code. The city is legally bound to a clear, harmonious tax formula:

$$\text{Assessed Value} = \text{Prevailing Market Value} \times \text{Assessment Level based on Actual Use}$$

Unfortunately, the proposed SMV drafts effectively look past this formula, shifting the assessment framework away from actual-use taxation toward speculative, redevelopment-based valuation.

2. The Guadalupe Architecture: Slicing Up Streets into Hyper-Granular Tax Traps

Nowhere is this shift more evident than in the raw data for Barangay Guadalupe. By moving away from a flat-rate model, the City Assessor has introduced an aggressive spatial architecture that uses rigid distance thresholds to maximize tax extraction.

Instead of an entire street sharing a uniform baseline, the new schedule implements a mathematical proximity-distance rule: properties on secondary interior roads are slammed with Commercial C-7 rates (Php30,000/sqm) if they fall within a strict 120-to-160-meter radius of a major transit junction. Cross that invisible line by a single meter, and the value drops to residential rates (PhP25,000/sqm).

   [PRIMARY URBAN CORRIDOR]
              │
              ├─► WITHIN 120–160 METERS ──► Classified as C-7 Commercial (₱30,000/sqm)
              │
              └─► BEYOND 120–160 METERS ───► Drops to R-2 / RS-4 Residential (₱25,000–₱20,000/sqm)

This creates an alarming scenario. If you own an ancestral family home that has been strictly residential for half a century, but your front door happens to fall inside that high-intensity 140-meter commercial box, your baseline land value automatically balloons by hundreds of percent. The city is essentially taxing your property based on its speculative development capacity and “Highest and Best Use” potential—running directly counter to actual-use statutory protection.

3. The Upland Speculative Paradox: Triggering Environmental Chaos

In our fragile upland districts, such as Barangay Busay and Barangay Babag, the proposed SMV spikes pose a serious policy contradiction that threatens our metropolitan climate resilience.

Historically, these areas have served as critical protected watersheds and ecological reserves. The city’s draft introduces staggering valuation jumps: a 900% spike along the Transcentral Highway and up to a 1,025% surge (reaching PhP45,000/sqm) in the premium hillside enclaves of Busay.

Here lies the paradox:

  • Keeping values artificially low allows passive land speculators to buy up vast tracks of environmental land for cheap and sit on them at zero cost, waiting to flip them to high-density developers.
  • However, spiking values by thousands of percent overnight creates an unsustainable tax burden for long-time upland residents and transitional properties. To survive the financial shock, they are forced to sell out or actively convert their eco-sensitive lands into intense, high-yield commercial tourism ventures and concrete developments.

Without targeted tax credits for environmental preservation, the city’s tax code will transform from a tool of revenue generation into a primary driver of upland urban sprawl and watershed degradation.

4. Turning a Cost Schedule into a Density Tax

The adjustments to the Schedule of Base Unit Construction Cost (SBUCC) display the exact same revenue-driven philosophy. Over the last 23 years, cumulative inflation trends in the Philippines justify a standard 2.1x to 2.4x increase in baseline construction material inputs.

While horizontal residential structures reasonably mirror this trend, high-density vertical condominiums face a jaw-dropping increase of 558% to 577% (surging up to PhP65,000/sqm for Category V-A).

The city is no longer using the SBUCC as a conservative structural replacement-cost index. Instead, it is factoring in the investment yield and vertical productivity of the real estate market. An inflated SBUCC that ignores real-world economic depreciation risks turning into a punitive penalty on urban modernization, driving up rental costs and business overhead across the board.

The Path Forward: Revenue with Equity

Modernizing Cebu City’s revenue system is necessary and long overdue to protect our local economy from predatory land hoarding. However, fiscal progress must not be achieved by executing a de facto repeal of taxpayer protections.

To ensure a balanced, lawful, and socially sustainable transition under RPVARA, the City Council and the Bureau of Local Government Finance (BLGF) must adopt structural safeguards:

  1. Codify Actual Use Discount Factors: Pass an explicit ordinance protecting frontage and proximity-split lots, ensuring that properties continuing low-density residential, institutional, or industrial operations are insulated from speculative commercial benchmarks.
  2. Establish Protected Subclasses: Introduce distinct categories for “Residential Frontage” and “Eco-Sensitive Upland Reserves” to shield vital watersheds and middle-income families from aggressive land capitalization.
  3. The Immediate Shield (The 6% Cap): For the first year of implementation, the city must implement a strict 6% cap on the total tax due compared to the previous year. This acts as an immediate safety valve for family checkbooks, ensuring that no matter how high the land’s theoretical value has risen, the actual cash leaving the taxpayer’s pocket remains manageable.
  4. The Structural Step-Up (The 3-to-5-Year Phase-in): While the true market value is locked into the city’s database from day one to keep speculators at bay, the actual taxable baseline should be phased in gradually over three to five years ( 40\% in Year 1, }70\% in Year 2, and 100\% in Year 3).
  5. Phase in Collection over 3-to-5 Years: Implement a gradual, step-up percentage layout to prevent a sudden economic shock from destabilizing the local housing market and displacing vulnerable populations.

Taxation must remain uniform, equitable, and progressive. If Cebu City allows its property assessment system to prioritize revenue maximization over structural fairness, it will score a temporary fiscal victory at the absolute cost of public confidence, environmental safety, and constitutional due process. It’s time for our policymakers to look past the valuation maps and protect the actual use of the people.